Smart Insulin Pens Market Summary
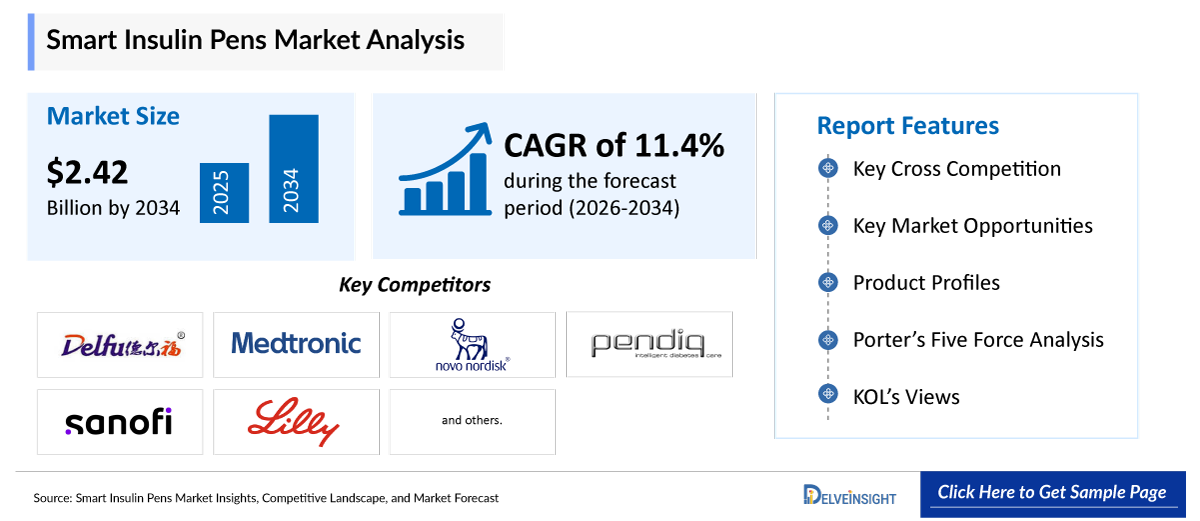
- The Smart Insulin Pens market is estimated at USD 0.92 billion in 2025 and is projected to reach USD 2.42 billion by 2034. Growth is anchored in the rising global burden of diabetes, growing patient and physician preference for connected, data-driven insulin delivery, and expanding integration between smart pens, continuous glucose monitors (CGMs), and digital diabetes-management platforms.
- The global Smart Insulin Pens market is growing at a CAGR of 11.4% during the forecast period from 2026 to 2034.
- By connectivity type, the Bluetooth-Enabled segment dominated the Smart Insulin Pens market with a 63% share in 2025.
- By end-user, the Hospitals & Clinics segment dominated the Smart Insulin Pens market with a 41% share in 2025.
- By distribution channel, the Hospital & Retail Pharmacy segment dominated the Smart Insulin Pens market with a 53% share in 2025.
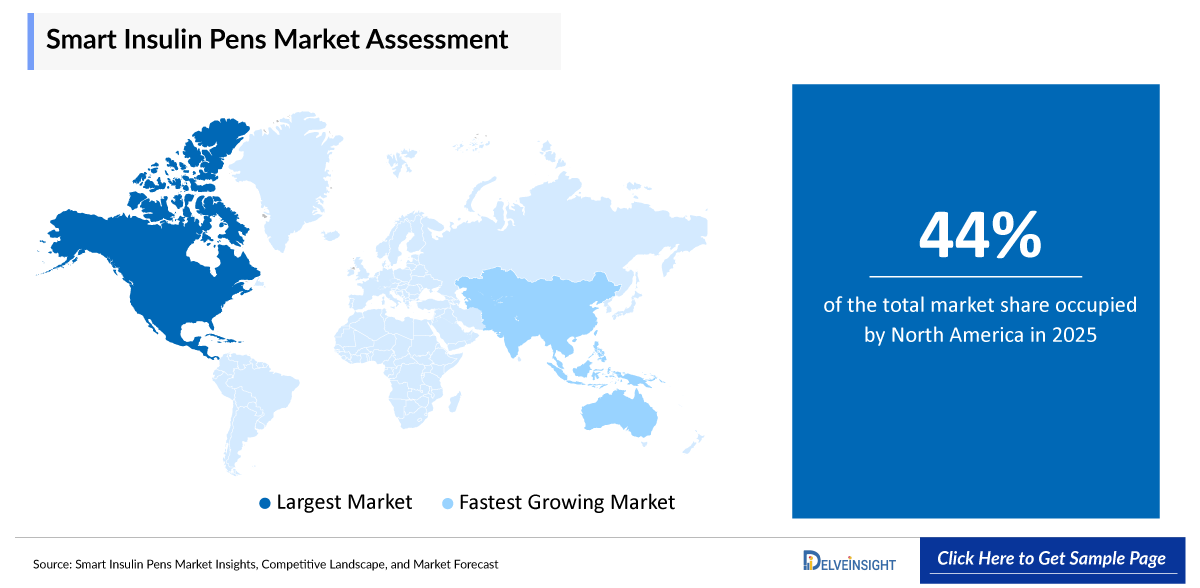
- North America dominated the global Smart Insulin Pens market revenue with a 44% share in 2025, representing the highest regional market share globally.
A smart insulin pen is a reusable or disposable insulin delivery device, or a connected add-on cap for a conventional pen, that automatically captures the dose, date, and time of each injection and transmits this information via Bluetooth, NFC, USB, or cloud connectivity to a companion mobile application. By digitizing insulin dosing, these devices support dose-tracking, missed-dose alerts, bolus calculation, insulin-on-board estimation, and integration with continuous glucose monitors, helping people with diabetes and their clinicians make more informed, data-backed treatment decisions. The market is organized by connectivity type across Bluetooth-enabled, NFC-enabled, USB-connected, and wireless/cloud-connected pens; by end-user, spanning hospitals and clinics, homecare settings, diabetes specialty centers, and ambulatory care centers; and by distribution channel, including hospital and retail pharmacies, diabetic clinics and centers, and e-commerce. Driven by the surging global diabetes population, rising demand for personalized digital diabetes management, and accelerating device-to-app and device-to-CGM connectivity, smart insulin pens are becoming an increasingly central component of the connected diabetes-care ecosystem.
Smart Insulin Pens Market Key Growth Drivers
- The rising global burden of diabetes is expanding the addressable patient population, with the International Diabetes Federation estimating 589 million adults living with diabetes in 2024, a figure projected to reach 853 million by 2050.
- Growing physician and patient preference for connected insulin delivery over conventional pens is accelerating adoption, as automatic dose-logging reduces missed or duplicated doses and improves treatment adherence.
- Expanding integration between smart insulin pens and continuous glucose monitoring systems, such as Medtronic InPen's compatibility with Dexcom and FreeStyle Libre sensors, is creating a data-rich, near-closed-loop management experience for people on multiple daily injections.
- Major insulin manufacturers, including Novo Nordisk, Sanofi, and Eli Lilly, are embedding connectivity directly into their branded insulin delivery ecosystems to strengthen patient retention and support value-based care contracting.
- Rising smartphone penetration and the proliferation of diabetes-management apps are lowering the adoption barrier for connected pens, particularly in homecare and ambulatory settings.
- Favorable reimbursement developments and expanding insurance coverage for connected insulin delivery devices in the United States and parts of Europe are improving affordability and prescription volumes.
- Growing merger, acquisition, and licensing activity, including Abbott's acquisition of Bigfoot Biomedical and Novo Nordisk's acquisition of Biocorp, is consolidating smart-pen technology within larger diabetes-care and pharmaceutical platforms and accelerating commercialization.
Key Companies in Smart Insulin Pens Market
The competitive landscape is led by the following active manufacturers:
- Emperra GmbH E-Health Technologies
- Jiangsu Delfu Medical Device Co., Ltd.
- Medtronic
- Novo Nordisk A/S
- Pendiq
- Sanofi
- Berlin-Chemie
- Bigfoot Biomedical
- Digital Medics Pty Ltd.
- Eli Lilly and Company
For illustrative purposes, only the top 10 companies are listed in the Table of Contents. The report may include analysis and references to additional companies relevant to the market assessment.
Smart Insulin Pens Market Size
The following snapshot summarizes the principal report metrics for the Smart Insulin Pens market.
|
Report Metrics |
Details |
|
2025 Market Size |
USD 0.92 billion |
|
2034 Projected Market Size |
USD 2.42 billion |
|
Growth Rate (2026-2034) |
11.4% CAGR |
|
Largest Market |
North America |
|
Fastest Growing Market |
Asia-Pacific |
|
Market Structure |
Moderately Fragmented |
All market values are expressed in USD and represent DelveInsight estimates synthesized from primary and secondary research.
Factors Contributing to the Growth of the Smart Insulin Pens Market
Market Drivers
Rising Global Diabetes Burden and Insulin-Dependent Population
The single most powerful driver of the Smart Insulin Pens market is the sheer scale and continued growth of the global diabetes population. The International Diabetes Federation estimates that 589 million adults were living with diabetes in 2024, equivalent to roughly one in nine adults worldwide, with the figure projected to rise to 853 million by 2050. A substantial share of this population, spanning both type 1 diabetes and insulin-requiring type 2 diabetes, relies on multiple daily insulin injections delivered by pen, creating a large and expanding installed base for connected pen technology. As insulin-treated populations grow across both developed and emerging markets, and as clinicians increasingly seek objective dosing data to guide therapy intensification, demand for smart insulin pens that automatically capture and transmit dosing information expands in step, anchoring market growth through 2034.
Growing Demand for Personalized, Data-Driven Diabetes Management
Smart insulin pens address a long-standing gap in diabetes care: the absence of objective, real-time insulin dosing data comparable to what continuous glucose monitors already provide for glucose levels. By automatically logging the size and timing of every injection, these devices eliminate manual dose diaries, reduce missed or duplicated doses, and allow both patients and healthcare providers to review injection history alongside glucose trends. This capability supports more personalized dose titration, better identification of patterns such as skipped basal doses, and more productive clinic visits. As payers and providers increasingly emphasize value-based, data-informed diabetes care, demand for the objective dosing record that smart pens provide continues to strengthen across both type 1 and type 2 diabetes populations.
Expanding Integration with Continuous Glucose Monitoring Systems
A defining trend reshaping the market is the deepening integration of smart insulin pens with continuous glucose monitoring (CGM) systems. Medtronic's InPen, for example, integrates with Dexcom G6 and G7 sensors as well as Abbott's FreeStyle Libre data to combine dosing and glucose information within a single bolus-calculator and insulin-on-board view. The Bigfoot Unity system, now part of Abbott, pairs a smart pen cap directly with the FreeStyle Libre 2 sensor to deliver on-demand, physician-directed dosing recommendations. This convergence of insulin dosing and glucose data creates what clinicians increasingly describe as a decision-support precursor to automated insulin delivery for people on multiple daily injections, and it is a central reason device makers are racing to expand CGM compatibility across their smart-pen portfolios.
Strategic Investment by Major Insulin and Pharmaceutical Manufacturers
The market's largest insulin manufacturers are treating connectivity as a core strategic priority rather than an optional add-on. Novo Nordisk markets the NovoPen 6 and NovoPen Echo Plus smart pens compatible with its Penfill insulin cartridges and acquired French connected-device specialist Biocorp in 2023 to broaden its smart-cap portfolio. Sanofi partnered with Biocorp to bring the Mallya-based SoloSmart cap to its SoloStar disposable pens, receiving FDA 510(k) clearance in January 2024. Eli Lilly developed the Tempo Personalized Diabetes Management Platform, pairing a Tempo Smart Button with prefilled Humalog, Lyumjev, and Basaglar pens. These investments by branded insulin manufacturers embed connectivity directly into insulin prescriptions, extending smart-pen reach well beyond the small standalone device makers that pioneered the category.
Rising Smartphone Penetration and Digital Health App Adoption
The proliferation of smartphones and diabetes-management applications is lowering the practical barrier to smart-pen adoption. Because most smart insulin pens rely on Bluetooth or NFC pairing with a companion app to display and share dosing data, rising smartphone ownership, even in price-sensitive and emerging markets, directly expands the population that can meaningfully use connected pen technology. Established diabetes app ecosystems such as mySugr, Glooko, and Roche's platforms have added smart-pen compatibility, giving patients a familiar interface through which to adopt connected devices without switching their broader diabetes-management workflow, further supporting uptake in homecare and ambulatory settings.
Consolidation and M&A Activity Accelerating Commercialization
Growing consolidation is concentrating smart-pen technology within larger, better-resourced diabetes-care platforms. Abbott's acquisition of Bigfoot Biomedical and Novo Nordisk's acquisition of Biocorp, developer of the Mallya and SoloSmart smart-cap platforms, illustrate how established medical device and pharmaceutical companies are absorbing specialized connected-pen innovators to accelerate regulatory clearance, manufacturing scale-up, and global distribution. This consolidation trend is expected to continue as device makers and insulin manufacturers seek to control the full connected-care value chain from insulin delivery through data analytics.
Market Restraints
Despite strong underlying momentum, the Smart Insulin Pens market faces material constraints. The higher upfront and per-unit cost of smart pens and connected add-on caps relative to conventional insulin pens remains a barrier to adoption, particularly in price-sensitive and emerging markets where out-of-pocket healthcare spending is high. Reimbursement for connected insulin delivery devices remains inconsistent across geographies, and coverage gaps can leave patients responsible for costs that limit uptake even where clinical benefit is well established. Data privacy and cybersecurity concerns associated with the transmission and storage of personal health and dosing information create hesitancy among some patients and providers, and interoperability challenges between different manufacturers' pens, apps, and CGM systems can fragment the user experience and complicate clinical workflows. Limited awareness of smart-pen technology among patients and even some healthcare providers in low- and middle-income regions constrains penetration outside established markets, and reliance on smartphone pairing excludes patients without consistent smartphone access. Eli Lilly's 2026 decision to discontinue its Tempo Personalized Diabetes Management Platform underscores the commercial and reimbursement uncertainty that can affect even well-resourced connected-pen programs. Together, these cost, reimbursement, data-security, interoperability, and awareness barriers temper the pace of adoption, even as the underlying drivers of rising diabetes prevalence and digital health adoption remain firmly intact.
Smart Insulin Pens Market Segment Analysis
The smart insulin pens market by connectivity type (bluetooth-enabled, nfc-enabled, usb-connected, wireless/cloud-connected), end-users (hospitals & clinics, homecare settings, diabetes specialty centers, ambulatory care centers, others), distribution channels (hospital & retail pharmacy, diabetic clinics & centers, e-commerce, others), and geography (North America, Europe, Asia-Pacific, and Rest of World).
By Connectivity Type
Dominant Subsegment: Bluetooth-Enabled.
The Bluetooth-enabled segment accounted for 63% of the Smart Insulin Pens market in 2025. Bluetooth-enabled pens are the leading connectivity type because Bluetooth Low Energy offers reliable, low-power, continuous pairing with smartphones, enabling automatic, real-time transfer of dosing data without requiring the patient to actively tap or scan the device. Leading products such as Medtronic's InPen, Novo Nordisk's NovoPen 6 and NovoPen Echo Plus, and Eli Lilly's Tempo Smart Button all rely on Bluetooth connectivity, giving the segment the deepest catalog of commercially available, clinically validated devices. Bluetooth's broad compatibility with both iOS and Android diabetes-management apps, together with its established role in CGM data transmission, makes it the natural default for manufacturers building integrated glucose-and-insulin data platforms. While NFC-enabled pens are the fastest-growing connectivity type, valued for their simplicity and lower power requirements in markets such as Germany where Emperra's ESYSTA pioneered Bluetooth-enabled dosing, the breadth of Bluetooth's device ecosystem and its central role in CGM integration secure the segment's leadership across the forecast period.
By End-Users
Dominant Subsegment: Hospitals & Clinics.
The hospitals & clinics segment accounted for 41% of the Smart Insulin Pens market in 2025. Hospitals and clinics are the leading end-user category because they serve as the primary point of diabetes diagnosis, insulin therapy initiation, and device prescription, giving endocrinologists and diabetes educators direct influence over which connected pens patients adopt. Clinical settings also generate the greatest immediate value from objective dosing data, since physicians use pen-generated injection histories to titrate therapy, identify adherence gaps, and support insurance documentation during in-person visits. Hospitals and specialty diabetes clinics were also the first sites to pilot smart-pen programs such as the Bigfoot Unity Program, reinforcing clinical familiarity and referral pathways. While homecare settings are the fastest-growing end-user category as more patients self-manage therapy at home with continuous app-based support, the central role of hospitals and clinics in device prescription and therapy titration secures the segment's leadership across the forecast period.
By Distribution Channel
Dominant Subsegment: Hospital & Retail Pharmacy.
The hospital & retail pharmacy segment accounted for 53% of the Smart Insulin Pens market in 2025. Hospital and retail pharmacies are the leading distribution channel because prescription-based insulin delivery devices are predominantly dispensed through pharmacy networks that can verify insurance coverage, manage prior authorizations, and provide patient counseling on proper device use. Hospital pharmacies benefit from direct integration with prescribing endocrinology and diabetes-care teams, while large retail pharmacy chains offer the scale and geographic reach needed to fulfil recurring insulin and device-consumable prescriptions. E-commerce is the fastest-growing distribution channel, supported by direct-to-patient digital health platforms and manufacturer-run online ordering programs that simplify reordering of compatible cartridges and disposable pens, but the reimbursement-linked, prescription-driven nature of insulin delivery keeps hospital and retail pharmacy channels dominant across the forecast period.
Smart Insulin Pens Market Region Analysis
Dominant Region: North America
North America accounted for 44% of the global Smart Insulin Pens market revenue in 2025, representing the highest regional market share globally. The region's dominance reflects a high prevalence of diagnosed diabetes, strong insurance and reimbursement coverage for connected insulin delivery devices, and the presence of leading manufacturers including Medtronic, Eli Lilly, and Abbott (following its acquisition of Bigfoot Biomedical). The United States in particular benefits from broad adoption of the InPen and Bigfoot Unity systems, extensive CGM penetration that creates natural pull-through demand for CGM-compatible smart pens, and FDA clearance pathways that have supported a steady stream of new connected-device launches. Strong direct-to-consumer digital health marketing, employer and payer-sponsored diabetes management programs, and deep integration with popular diabetes apps further reinforce the region's leadership across the forecast period.
Fastest Growing Region: Asia-Pacific
Asia-Pacific is the fastest-growing region in the Smart Insulin Pens market. The region's elevated CAGR is driven by its enormous and rapidly growing diabetic population, led by China and India, alongside rising healthcare expenditure, expanding private insurance coverage, and growing local manufacturing capability. China's Jiangsu Delfu Medical Device Co., Ltd. is scaling domestic production of connected insulin delivery devices, Japan is seeing steady adoption of digital diabetes-management tools within its advanced healthcare system, and India's large and increasingly urban diabetic population is driving demand for affordable connected pens and smart-cap add-ons. Government initiatives to modernize chronic-disease management and growing awareness of digital health tools among both patients and physicians are accelerating adoption, positioning Asia-Pacific as the principal source of incremental market growth over the forecast period.
Regional Commentary
North America
North America accounted for 44% of the global Smart Insulin Pens market revenue in 2025. The United States dominates on the strength of its high diagnosed-diabetes prevalence, favorable device reimbursement, deep CGM penetration, and the concentration of leading manufacturers including Medtronic, Eli Lilly, and Abbott, while Canada contributes steady growth supported by its public healthcare system's gradual expansion of connected-device coverage.
Europe
Europe is a large and technologically advanced regional market, anchored by Germany, home to Emperra GmbH E-Health Technologies, whose ESYSTA pen was among the first Bluetooth-enabled smart insulin pens to receive European Commission approval, and Pendiq, another German developer of connected insulin delivery devices. Berlin-Chemie and Sanofi's SoloSmart, developed with Biocorp, extend the region's connected-pen footprint across Germany, France, the United Kingdom, Italy, and Spain, supported by established EU medical device regulatory frameworks and growing statutory health-insurance coverage for digital diabetes tools.
Asia-Pacific
Asia-Pacific is the fastest-growing region, propelled by its large and expanding diabetic population across China, Japan, India, South Korea, and Australia. China's Jiangsu Delfu Medical Device Co., Ltd. is expanding domestic manufacturing and distribution of connected insulin pens, Japan's advanced healthcare infrastructure supports steady premium-device adoption, and India's growing private healthcare and insurance sector is broadening access to smart insulin delivery technology, together accelerating regional market growth.
Rest of World
The Rest of World region, spanning Latin America, the Middle East, and Africa, is an emerging growth frontier for smart insulin pens. Rising diabetes prevalence, gradually improving healthcare infrastructure, and growing awareness of digital diabetes-management tools, led by companies such as Digital Medics Pty Ltd., extending connectivity solutions into new markets, are broadening access, while international distribution partnerships and expanding private insurance coverage support the gradual build-out of regional demand.
Smart Insulin Pens Market Competitive Landscape
The Smart Insulin Pens market is classified as Moderately Fragmented. A group of large, diversified medical device and pharmaceutical companies with global distribution, including Medtronic, Novo Nordisk A/S, Sanofi, and Eli Lilly and Company, anchor the top tier by embedding connectivity into branded insulin ecosystems, while specialized connected-device developers such as Emperra GmbH E-Health Technologies, Pendiq, Berlin-Chemie, Bigfoot Biomedical, Jiangsu Delfu Medical Device Co., Ltd., and Digital Medics Pty Ltd. compete through focused smart-cap and smart-pen innovation, regional manufacturing strength, and niche connectivity partnerships.
The competitive landscape can be evaluated across the following dimensions:
- Market concentration: Moderately fragmented, with large insulin and device manufacturers leading distribution scale alongside specialized connected-pen innovators.
- Leading players: Medtronic, Novo Nordisk A/S, Sanofi, and Eli Lilly and Company anchor the top tier through branded insulin ecosystem integration and global reach.
- Geographic reach: Leaders operate global distribution networks, while regional specialists such as Emperra, Pendiq, and Berlin-Chemie maintain strong footholds in the German and broader European market.
- Product portfolio strength: Top players offer integrated pen-plus-app-plus-CGM ecosystems spanning dose logging, bolus calculation, and insulin-on-board tracking.
- Connectivity technology: Ownership of validated Bluetooth, NFC, and cloud-connectivity platforms, together with CGM interoperability, is a decisive competitive advantage.
- Strategic partnerships: Tie-ups between insulin manufacturers and device or app developers, such as Sanofi and Biocorp's SoloSmart and Medtronic InPen's Dexcom and FreeStyle Libre integrations, extend ecosystem reach.
- M&A activity: Active consolidation, including Abbott's acquisition of Bigfoot Biomedical and Novo Nordisk's acquisition of Biocorp, is concentrating connected-pen technology within larger diabetes-care platforms.
- Manufacturing capabilities: Precision dose-sensing electronics, miniaturized Bluetooth and NFC modules, and regulatory-grade quality manufacturing are key competitive moats.
- Innovation focus: CGM integration, AI-assisted dose guidance, expanded smartphone and wearable compatibility, and next-generation smart-cap retrofits for disposable pens.
Smart Insulin Pens Market Recent Developmental Activities
In 2026, Eli Lilly and Company announced the discontinuation of its Tempo Personalized Diabetes Management Platform, including the Tempo Smart Button, Tempo Pens, and TempoSmart app, by the end of 2026, shifting affected patients toward standard KwikPen insulin delivery and the Lilly Insulin Value Savings Card. Strategic significance: Signals the commercial and reimbursement challenges connected-pen programs can face even when backed by a major insulin manufacturer.
In January 2024, Biocorp (a Novo Nordisk company) obtained U.S. FDA 510(k) clearance for SoloSmart, the Sanofi-branded smart cap for disposable SoloStar insulin pens, marking the second FDA clearance for Biocorp's Mallya connectivity platform. Strategic significance: Expands U.S. market access for Sanofi's connected insulin delivery ecosystem and reinforces Biocorp's Mallya platform as a cross-brand connectivity layer.
In 2023, Novo Nordisk A/S completed the acquisition of Biocorp SA, the French developer of the Mallya smart-cap platform used across Novo Nordisk, Sanofi, and Roche Diabetes Care partnerships. Strategic significance: Brings smart-pen connectivity technology in-house and strengthens Novo Nordisk's digital diabetes-care portfolio.
In 2023, Abbott acquired smart insulin pen cap maker Bigfoot Biomedical, building on the companies' existing FreeStyle Libre integration partnership behind the Bigfoot Unity Diabetes Management System. Strategic significance: Combines Abbott's CGM leadership with Bigfoot's dose-decision-support smart-cap technology to strengthen its connected diabetes-care ecosystem.
Smart Insulin Pens Market Segmentation
Smart Insulin Pens Market by Connectivity Type
- Bluetooth-Enabled
- NFC-Enabled
- USB-Connected
- Wireless/Cloud-Connected
Smart Insulin Pens Market by End-Users
- Hospitals & Clinics
- Homecare Settings
- Diabetes Specialty Centers
- Ambulatory Care Centers
- Others
Smart Insulin Pens Market by Distribution Channels
- Hospital & Retail Pharmacy
- Diabetic Clinics & Centers
- E-commerce
- Others
Smart Insulin Pens Market by Geography
- North America Smart Insulin Pens Market
- United States Smart Insulin Pens Market Size in USD million (2023-2034)
- Canada Smart Insulin Pens Market Size in USD million (2023-2034)
- Mexico Smart Insulin Pens Market Size in USD million (2023-2034)
- Europe Smart Insulin Pens Market
- Germany Smart Insulin Pens Market Size in USD million (2023-2034)
- United Kingdom Smart Insulin Pens Market Size in USD million (2023-2034)
- France Smart Insulin Pens Market Size in USD million (2023-2034)
- Italy Smart Insulin Pens Market Size in USD million (2023-2034)
- Spain Smart Insulin Pens Market Size in USD million (2023-2034)
- Rest of Europe Smart Insulin Pens Market Size in USD million (2023-2034)
- Asia-Pacific Smart Insulin Pens Market
- China Smart Insulin Pens Market Size in USD million (2023-2034)
- Japan Smart Insulin Pens Market Size in USD million (2023-2034)
- India Smart Insulin Pens Market Size in USD million (2023-2034)
- Australia Smart Insulin Pens Market Size in USD million (2023-2034)
- South Korea Smart Insulin Pens Market Size in USD million (2023-2034)
- Rest of Asia-Pacific Smart Insulin Pens Market Size in USD million (2023-2034)
- Rest of the World (RoW) Smart Insulin Pens Market
- Middle East Smart Insulin Pens Market Size in USD million (2023-2034)
- Africa Smart Insulin Pens Market Size in USD million (2023-2034)
- South America Smart Insulin Pens Market Size in USD million (2023-2034)
Smart Insulin Pens Market Recent Industry Trends and Milestones (2023-2026)
|
Category |
Key Developments |
|
Smart Insulin Pens Market Product Approval |
Regulatory momentum continued to expand device availability. Biocorp obtained FDA 510(k) clearance for SoloSmart, Sanofi's smart cap for SoloStar pens, in January 2024, and the Bigfoot Unity Diabetes Management System, cleared by the FDA in 2021, continued to expand its compatible-pen roster across major U.S. insulin brands. Novo Nordisk's NovoPen 6 and NovoPen Echo Plus and Medtronic's InPen remain the most widely available cleared devices across the United States and Europe, while Eli Lilly's 2026 discontinuation of its Tempo platform illustrates the evolving regulatory and commercial landscape for connected pens. |
|
Smart Insulin Pens Market Expansion |
Manufacturers broadened connectivity and app-integration capability across the value chain. Medtronic expanded InPen's CGM compatibility to include Dexcom G6 and G7 alongside FreeStyle Libre data, Novo Nordisk and Roche extended companion-app partnerships including mySugr and Glooko, and German developers Emperra and Pendiq continued to expand their domestically focused connected-pen platforms. Growing smart-cap retrofit options, such as Biocorp's Mallya, are extending connectivity to conventional disposable pens without requiring a full device replacement. |
|
Smart Insulin Pens Market Investment |
Consolidation accelerated as larger diabetes-care and pharmaceutical companies absorbed specialized connected-pen innovators. Novo Nordisk completed its acquisition of Biocorp in 2023, and Abbott acquired Bigfoot Biomedical the same year, building on their existing FreeStyle Libre integration partnership. Insulet's licensing payment to Bigfoot for pump-based automated insulin delivery technology further reflects growing cross-licensing activity between smart-pen and smart-pump developers as the connected diabetes-device ecosystem consolidates. |
|
Company Strategy |
Medtronic: CGM-integrated InPen platform with broad Dexcom and Libre compatibility. Novo Nordisk A/S: NovoPen 6/Echo Plus portfolio reinforced by the Biocorp acquisition. Sanofi: SoloSmart smart cap developed with Biocorp for SoloStar pens. Eli Lilly and Company: Tempo platform wind-down in 2026 in favor of standard KwikPen delivery. Emperra GmbH E-Health Technologies and Pendiq: German-market-focused Bluetooth-enabled pen specialists. Berlin-Chemie, Bigfoot Biomedical, Jiangsu Delfu Medical Device Co., Ltd., and Digital Medics Pty Ltd.: Regional and specialized connected-device strategies spanning Europe, North America, Asia-Pacific, and beyond. |
|
Emerging Technologies |
CGM integration is the leading edge of innovation, with bolus calculators, insulin-on-board tracking, and near-closed-loop decision support expanding across leading smart-pen platforms. NFC-enabled and smart-cap retrofit devices are emerging as lower-cost, lower-power alternatives to fully integrated Bluetooth pens, while cloud-connected platforms are enabling richer remote patient-monitoring and telehealth workflows. AI-assisted dose guidance, expanded wearable and smartwatch notifications, and improved interoperability standards between pens, apps, and CGMs are expected to define the next phase of product differentiation. |
Smart Insulin Pens Market Startup Funding and Investment Trends
Investment in the Smart Insulin Pens ecosystem has concentrated on CGM-integrated dose-decision support, smart-cap retrofit technology for disposable pens, and cloud-connected diabetes-management platforms. The following companies illustrate recent funding and investment activity and technology focus.
|
Company |
Total Funding |
Funding Stage |
Main Offering |
Core Technology |
|
Biocorp SA (Novo Nordisk Company) |
Acquired by Novo Nordisk (2023) |
Acquired |
Smart pen add-on caps (Mallya / SoloSmart) |
Bluetooth dose-logging smart cap platform |
|
Request for unlocking the report of the @ Smart insulin Pens Market | ||||
Capital continues to flow toward providers that combine connected-pen hardware with CGM interoperability and clinical decision support. Novo Nordisk's acquisition of Biocorp and Abbott's acquisition of Bigfoot Biomedical, both completed in 2023, underscore the strategic value large device and pharmaceutical companies place on connected insulin delivery technology. Emerging providers such as Diabnext are scaling app-connected pen caps, while established regional specialists including Emperra, Pendiq, Jiangsu Delfu Medical Device Co., Ltd., and Digital Medics Pty Ltd. continue to expand smart-pen manufacturing and distribution capacity. Collectively, these investments signal conviction that CGM integration, smart-cap retrofits, and cloud-connected data platforms will define the next phase of competitive advantage in the global Smart Insulin Pens market.
Key Takeaways from the Smart Insulin Pens Market Report Study
- Market size analysis for the current Smart Insulin Pens market size (2025), and market forecast for 9 years (2026 to 2034).
- Top key product/technology developments, mergers, acquisitions, partnerships, and joint ventures that happened over the last 3 years.
- Key companies dominating the global Smart Insulin Pens market.
- Various opportunities available for competitors in the Smart Insulin Pens market space.
- What are the top-performing segments in 2025? How will these segments perform in 2034?
- Which are the top-performing regions and countries in the current Smart Insulin Pens market scenario?
- Which are the regions and countries where companies should concentrate their opportunities for Smart Insulin Pens market growth in the future?
Target audience who can benefit from this Smart Insulin Pens market report study
- Smart Insulin Pens product providers
- Research organizations and consulting companies
- Smart Insulin Pens therapeutics-related organizations, associations, forums, and other alliances
- Government and corporate offices
- Start-up companies, venture capitalists, and private equity firms
- Distributors and traders dealing in Smart Insulin Pens
- Various end-users who want to know more about the Smart Insulin Pens market and the latest technological developments in the Smart Insulin Pens market.