Ultrasound Needle Guides Market Summary
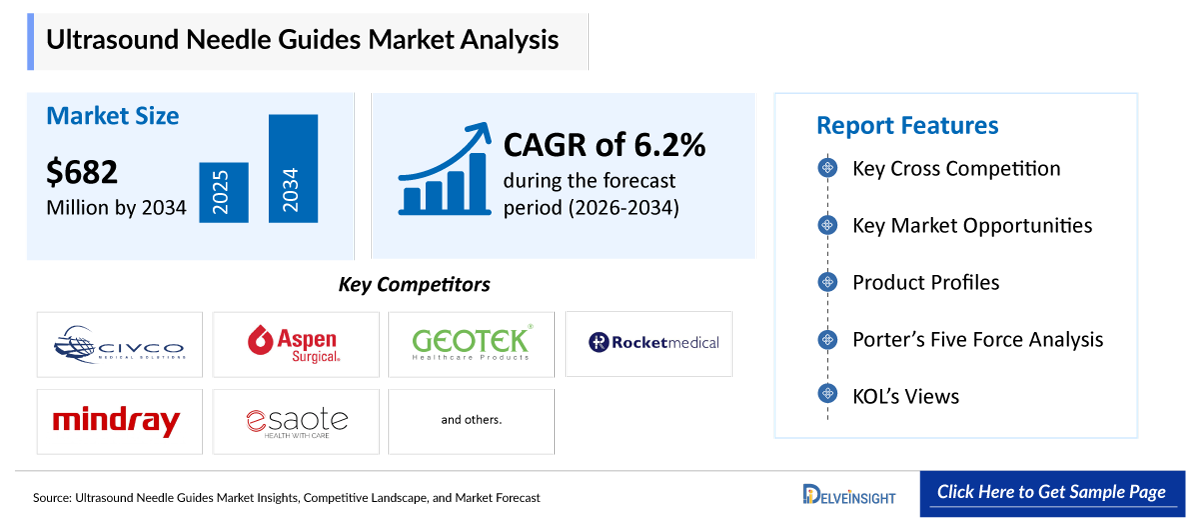
- The Ultrasound Needle Guides Market is estimated at USD 398 million in 2025 and is projected to reach USD 682 million by 2034. Growth is anchored in the rising global volume of ultrasound-guided interventional procedures, expanding point-of-care ultrasound (POCUS) adoption, and increasing clinician preference for single-use, infection-controlled guidance accessories.
- The Global Ultrasound Needle Guides Market is growing at a CAGR of 6.2% during the forecast period from 2026 to 2034.
Ultrasound Needle Guides Market Trends and Insights
- By product type, the disposable ultrasound needle guides segment dominated the Ultrasound Needle Guides market with a 74% share in 2025.
- By needle guidance mechanism, the in-plane needle guides segment dominated the Ultrasound Needle Guides market with a 57% share in 2025.
- By application, the biopsy procedures segment dominated the Ultrasound Needle Guides market with a 36% share in 2025.
- By end-user, the hospitals & clinics segment dominated the Ultrasound Needle Guides market with a 58% share in 2025.
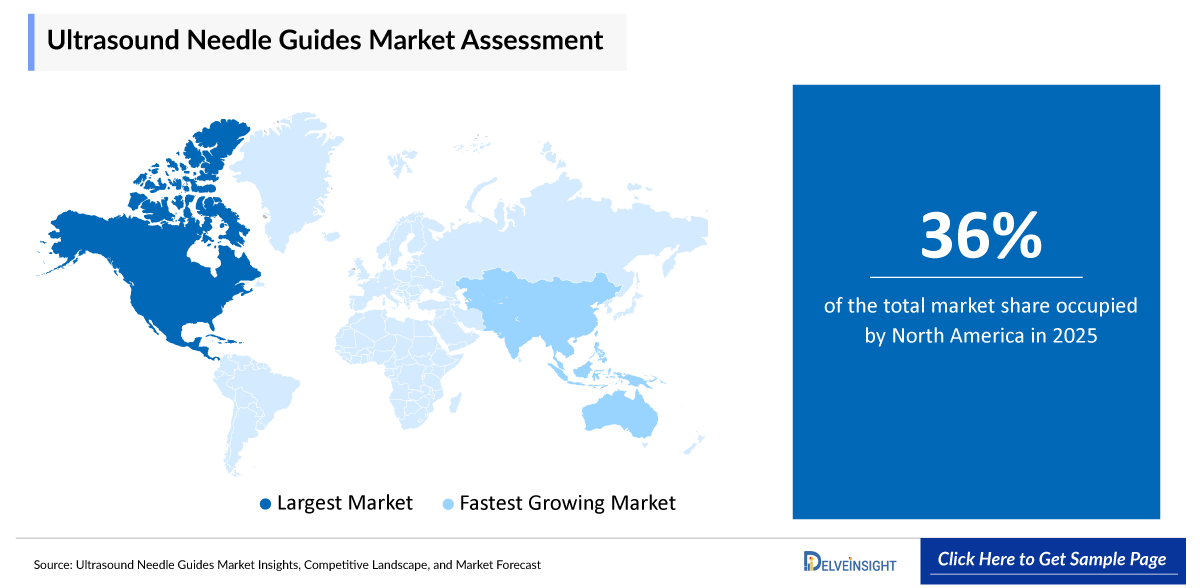
- North America dominated the global Ultrasound Needle Guides market revenue with a 36% share in 2025, representing the highest regional market share globally.
Request to unlock the Sample Page of the "Ultrasound Needle Guides Market"
Ultrasound Needle Guides Market Size
The following snapshot summarizes the principal report metrics for the Ultrasound Needle Guides market.
|
Report Metrics |
Details |
|
2025 Market Size | |
|
2034 Projected Market Size | |
|
Growth Rate (2026-2034) | |
|
Largest Market |
North America |
|
Fastest Growing Market |
Asia-Pacific |
|
Market Structure |
Fragmented |
All market values are expressed in USD and represent DelveInsight estimates synthesized from primary and secondary research.
Factors Contributing to the Growth of the Ultrasound Needle Guides Market
Ultrasound Needle Guides Market Drivers
-
Rising Volume of Ultrasound-Guided Interventional Procedures
The most powerful driver of the Ultrasound Needle Guides market is the sustained rise in ultrasound-guided diagnostic and interventional procedure volumes. Ultrasound guidance is now the clinical standard for a wide range of biopsies, fluid aspirations, catheter placements, and regional anesthesia procedures, because it delivers real-time visualization without ionizing radiation, at lower cost than CT or MRI guidance. The American Cancer Society projects more than 2 million new cancer diagnoses in the United States in 2025 alone, and each diagnostic pathway typically requires tissue confirmation through image-guided biopsy. As procedure volumes climb across oncology, urology, hepatology, and vascular access, the consumption of both reusable brackets and single-use guidance inserts rises directly, anchoring market growth through 2034.
-
Growing Prevalence of Chronic Disease and an Aging Population
The rising global burden of cancer, cardiovascular disease, and diabetes is expanding demand for precise, minimally invasive interventions that needle guides support. Prostate, liver, breast, and thyroid biopsies, along with vascular access and dialysis-catheter placement in an aging, comorbid population, depend on stable needle trajectories to reduce complications and repeat attempts. As chronic disease prevalence and the elderly population base continue to grow across developed and emerging markets alike, the underlying volume of guided procedures - and the accessories that support them - expands in step, sustaining durable long-term demand.
-
Rapid Expansion of Point-of-Care Ultrasound (POCUS)
The proliferation of compact, point-of-care ultrasound systems across emergency medicine, critical care, anesthesiology, and outpatient clinics is broadening the addressable base for needle guides well beyond traditional radiology suites. POCUS adoption supports bedside vascular access, nerve blocks, and aspiration procedures performed by a growing base of non-radiologist clinicians who rely on low-cost, easy-to-attach disposable guides to standardize technique and improve first-pass success. As POCUS platforms continue to proliferate across care settings, this decentralization of ultrasound-guided procedures is a structural tailwind for guide volumes through the forecast period.
-
Rising Prostate Biopsy Incidence and Transperineal Adoption
Growing awareness of prostate cancer screening and a clinical shift toward the transperineal biopsy approach are expanding demand for specialized guides. Transperineal biopsy, supported by products such as CIVCO's TP Pivot Pro disposable guide and introducer needle system, can reduce infection risk relative to the transrectal approach and is gaining favor among urologists. As transperineal adoption increases across hospitals and ambulatory urology practices, demand for purpose-built, freehand-compatible needle guidance systems is rising correspondingly, reinforcing growth in the biopsy application segment.
-
Structural Shift Toward Single-Use, Infection-Controlled Accessories
Hospitals and ambulatory surgical centers are increasingly standardizing on single-use, disposable needle guides to eliminate reprocessing burden and reduce cross-contamination risk. Disposable inserts paired with reusable, probe-specific brackets, the two-part design popularized by systems such as CIVCO's Ultra-Pro II, allow facilities to combine the cost efficiency of a durable bracket with the infection-control benefit of a sterile, single-use guide. As infection-prevention protocols tighten across hospitals, diagnostic imaging centers, and ASCs, this shift continues to favor the disposable product category and sustains recurring, per-procedure consumption.
-
Continuing Innovation in AI-Assisted and Tracking-Enabled Guidance
Manufacturers are increasingly embedding intelligence into needle guidance to improve accuracy and reduce operator dependency. AI-assisted trajectory mapping, adjustable multi-angle mechanisms that allow height and angle changes without removing the needle from the guide, and electromagnetic needle-tip tracking fused with live ultrasound imaging are expanding the clinical capability of guided procedures, particularly in prostate, liver, and vascular access applications. As OEMs and specialized accessory makers continue to differentiate through tracking and software integration, premium reusable and tracking-enabled guide categories are expected to grow faster than the market overall, even as the disposable category retains the largest share.
-
Expanding Use in Regional Anesthesia and Pain Management
Growing adoption of ultrasound-guided regional anesthesia and nerve block techniques, driven by enhanced-recovery-after-surgery protocols and efforts to reduce reliance on systemic opioids, is expanding a distinct and fast-growing application for needle guides. Anesthesiologists and pain-management specialists increasingly rely on in-plane guidance to maintain continuous needle-tip visibility during nerve block placement, supporting both procedural safety and post-operative pain control. As opioid-sparing anesthesia protocols become more widespread across surgical and chronic pain-management settings, this application is expected to post above-average growth through the forecast period.
Ultrasound Needle Guides Overview
An ultrasound needle guide is a mechanical or tracking-enabled accessory attached to an ultrasound transducer that establishes a fixed, predictable trajectory for a needle during image-guided interventional procedures. By keeping the needle aligned within the ultrasound beam plane, needle guides shorten procedure time, improve real-time needle-tip visualization, reduce the number of re-insertion attempts, and lower the risk of complications compared with unguided freehand technique.
Because ultrasound-guided interventions span a wide range of clinical settings, from bedside vascular access to prostate and liver biopsy suites, sponsors and hospital systems rely on a broad ecosystem of probe-specific reusable brackets, single-use disposable inserts, and sterile procedure kits supplied by specialized accessory manufacturers and diversified ultrasound OEMs alike. The market is organized by product type across reusable, disposable, sterile, and non-sterile guides; by needle guidance mechanism across in-plane, out-of-plane, adjustable-angle, and fixed-angle systems; by application, led by biopsy procedures alongside anesthesia and nerve blocks, aspiration procedures, and pain management; and by end-user, led by hospitals and clinics alongside ambulatory surgical centers and diagnostic imaging centers.
Driven by the rising global burden of cancer and chronic disease, the expansion of point-of-care ultrasound into outpatient and critical-care settings, and continuing innovation in AI-assisted trajectory mapping and electromagnetic tracking, ultrasound needle guides have become an essential, high-frequency accessory category underpinning safe and efficient image-guided care.
Ultrasound Needle Guides Market Key Growth Drivers
- The rising global volume of ultrasound-guided interventional procedures is driving demand, with the American Cancer Society projecting more than 2 million new cancer cases in the United States alone in 2025, sustaining high volumes of image-guided biopsy and aspiration procedures.
- Growing prevalence of chronic diseases, including cancer, cardiovascular disease, and diabetes, alongside an aging population, is expanding demand for precise, minimally invasive diagnostic and therapeutic interventions.
- Rapid expansion of point-of-care ultrasound (POCUS) across critical care, outpatient, and emergency settings is broadening the addressable base for compact, easy-to-use disposable needle guides.
- Rising incidence of prostate biopsies and growing clinical adoption of the transperineal biopsy approach, supported by products such as CIVCO's TP Pivot Pro, are expanding freehand and guide-assisted procedure volumes.
- A structural shift toward single-use, disposable guidance accessories is accelerating as hospitals prioritize infection control and eliminate reprocessing and sterilization burden.
- Continuing innovation in AI-assisted trajectory mapping, adjustable multi-angle mechanisms, and electromagnetic needle-tip tracking fused with ultrasound imaging is improving procedural accuracy and clinician confidence.
- Growing volumes of ultrasound-guided regional anesthesia and nerve block procedures, driven by enhanced-recovery and opioid-sparing pain-management protocols, are expanding demand across surgical and pain-management settings.
- Strategic OEM partnerships and acquisitions, including platform-embedded guidance software and robotic-assisted integration, are expected to sustain steady growth in the market through 2034.
Major Ultrasound Needle Guides Companies
The Ultrasound Needle Guides Competitive Landscape is led by the following active manufacturers:
- CIVCO Medical Solutions
- Aspen Surgical
- Geotek Medical
- Rocket Medical
- Mindray
- Esaote
- GE HealthCare
- Siemens Healthineers
- Becton, Dickinson and Company (BD)
- Argon Medical Devices
- Veran Medical Technologies
For illustrative purposes, only the top 10 companies are listed in the Table of Contents. The report may include analysis and references to additional companies relevant to the market assessment.
Ultrasound Needle Guides Market Restraints
Despite steady momentum, the Ultrasound Needle Guides market faces material constraints. The proliferation of probe-specific bracket and guide designs across competing ultrasound OEMs creates compatibility fragmentation, requiring accessory manufacturers to maintain extensive product lines and complicating standardization for multi-vendor hospital systems. Clinician preference for unguided freehand technique in certain high-volume, low-complexity procedures, particularly among highly experienced operators, limits guide attachment rates in some settings.
Pricing pressure from group purchasing organizations and hospital procurement consolidation compresses margins for commodity disposable guides, while reimbursement for the underlying guided procedures varies across geographies and payer systems. Stringent regulatory requirements, including FDA 510(k) clearance and international quality-system certification for each probe-specific configuration, lengthen product-development timelines and raise compliance costs.
Slower adoption of premium tracking-enabled and reusable guide categories in price-sensitive and emerging markets, combined with competition from alternative guidance technologies such as robotic-assisted and stereotactic navigation platforms in select high-acuity applications, further tempers growth. Together, these compatibility, pricing, regulatory, and competitive dynamics moderate the pace of expansion, even as the underlying drivers of procedure-volume growth, POCUS adoption, and infection-control preference remain firmly intact.
Ultrasound Needle Guides Market Segment Analysis
The ultrasound needle guides market by product type (reusable ultrasound needle guides, disposable ultrasound needle guides, sterile ultrasound needle guides, non-sterile ultrasound needle guides), needle guidance mechanism (in-plane needle guides, out-of-plane needle guides, adjustable-angle needle guides, fixed-angle needle guides), application (anesthesia & nerve blocks, biopsy procedures, aspiration procedures, pain management, others), end-users (hospitals & clinics, ambulatory surgical centers (ascs), diagnostic imaging centers, others), and geography (North America, Europe, Asia-Pacific, and Rest of World).
-
Ultrasound Needle Guides Market Segmentation By Product Type
Dominant Subsegment: Disposable Ultrasound Needle Guides.
The disposable ultrasound needle guides segment accounted for approximately 74% of the Ultrasound Needle Guides market in 2025. Disposable guides are the leading product type because hospitals and ambulatory facilities increasingly prioritize infection control and eliminate the labor, cost, and turnaround burden of reprocessing between procedures. The two-part design popularized by systems such as CIVCO's Ultra-Pro II, pairing a durable, probe-specific reusable bracket with a sterile, single-use snap-on guide, allows facilities to combine cost efficiency with per-procedure sterility assurance.
High-frequency applications such as vascular access, fine-needle aspiration, and regional anesthesia particularly favor disposables given their procedure volume and turnaround requirements. While reusable guides are growing at the fastest rate as tracking-enabled and premium multi-angle systems gain clinical traction in specialized biopsy and interventional-radiology settings, the sheer procedure volume and infection-control preference secure the disposable segment's leadership across the forecast period.
-
Ultrasound Needle Guides Market Segmentation By Needle Guidance Mechanism
Dominant Subsegment: In-Plane Needle Guides.
The in-plane needle guides segment accounted for approximately 57% of the Ultrasound Needle Guides market in 2025. In-plane guidance is the leading mechanism because it keeps the entire needle shaft and tip continuously visible within the ultrasound beam plane throughout advancement, which is the preferred technique for regional anesthesia and nerve block procedures, vascular access, and many superficial biopsy applications where continuous needle-tip visualization is critical to safety.
Clinical training programs and professional society guidelines widely favor in-plane technique for novice and experienced operators alike, reinforcing its adoption across hospitals and outpatient settings. Adjustable-angle guides are the fastest-growing mechanism, as they allow clinicians to modify needle trajectory without withdrawing and repositioning the instrument, an increasingly valued feature in prostate and deep-organ biopsy. Out-of-plane and fixed-angle guides retain steady niche demand in specific deep-target and endocavity applications. Nonetheless, the versatility and safety profile of in-plane guidance secure its leadership across the forecast period.
-
Ultrasound Needle Guides Market Segmentation By Application
Dominant Subsegment: Biopsy Procedures.
The biopsy procedures segment accounted for approximately 36% of the Ultrasound Needle Guides market in 2025. Biopsy procedures lead the application mix because tissue-diagnosis pathways for prostate, breast, liver, thyroid, and renal disease depend heavily on ultrasound-guided core-needle and fine-needle sampling, and the rising global cancer burden sustains high, recurring biopsy volumes. The growing clinical adoption of the transperineal prostate biopsy approach, supported by dedicated systems such as CIVCO's TP Pivot Pro, is further expanding guide-assisted procedure counts.
Anesthesia and nerve blocks form a large and fast-growing application as opioid-sparing regional anesthesia protocols spread across surgical and pain-management settings, while aspiration procedures and pain-management interventions such as joint and spine injections contribute steady incremental demand. Given the depth of the oncology diagnostic pipeline and the procedural complexity that favors guide-assisted accuracy, biopsy procedures are expected to retain clear leadership across the forecast period.
-
Ultrasound Needle Guides Market Segmentation By End-Users
Dominant Subsegment: Hospitals & Clinics.
The hospitals & clinics segment accounted for approximately 58% of the Ultrasound Needle Guides market in 2025. Hospitals and clinics remain the leading end-user because they perform the broadest and highest-volume range of ultrasound-guided procedures, spanning radiology, urology, oncology, anesthesiology, and emergency medicine, and maintain the capital-equipment base and cyclotron-adjacent imaging infrastructure needed to support complex interventional cases. Large hospital systems also benefit from group purchasing agreements with manufacturers such as CIVCO, BD, and GE HealthCare that standardize guide selection across departments.
Ambulatory surgical centers are the fastest-growing end-user as outpatient migration of biopsy, pain-management, and regional anesthesia procedures accelerates, favoring compact, disposable guide formats and bundled sterile procedure kits from suppliers such as Aspen Surgical. Diagnostic imaging centers contribute steady, imaging-focused demand, particularly for breast, thyroid, and abdominal biopsy. Nonetheless, the scale and procedural breadth of hospitals and clinics secure their leadership across the forecast period.
Ultrasound Needle Guides Market Region Analysis
- Dominant Region: North America
North America accounted for 36% of the global Ultrasound Needle Guides market revenue in 2025, representing the highest regional market share globally. The region's dominance reflects a mature interventional-radiology and point-of-care ultrasound ecosystem, high per-capita procedure volumes, a dense hospital and ambulatory surgical center network, and clear FDA 510(k) regulatory pathways, particularly in the United States. North America hosts the largest installed base of ultrasound systems from GE HealthCare, Siemens Healthineers, and other major OEMs, and benefits from proximity to leading accessory manufacturers such as CIVCO Medical Solutions, Aspen Surgical, and Argon Medical Devices.
Rising cancer screening rates, growing adoption of the transperineal prostate biopsy approach, and expanding point-of-care ultrasound use across emergency medicine and critical care drive substantial guide consumption. Strong reimbursement for image-guided procedures, well-established clinician training infrastructure, and continued product innovation anchor the region's continued leadership across the forecast period.
- Fastest Growing Region: Asia-Pacific
Asia-Pacific is the fastest-growing region in the Ultrasound Needle Guides market. The region's elevated CAGR is driven by rising cancer incidence, rapid expansion of hospital and diagnostic imaging infrastructure, and growing healthcare investment across China, Japan, India, South Korea, and Australia. China is expanding its base of installed ultrasound systems and interventional-radiology capacity, Japan is advancing point-of-care ultrasound adoption in outpatient and critical-care settings, India is scaling low-cost biopsy and diagnostic imaging services alongside a growing base of ambulatory surgical centers, and South Korea and Australia are adopting premium tracking-enabled guidance systems in leading academic hospitals.
Government healthcare investment, an expanding oncology patient population, and growing local manufacturing by regional OEMs such as Mindray are accelerating adoption, while regional distributors increasingly partner with global accessory manufacturers to broaden probe-specific coverage. The combination of high disease burden, infrastructure build-out, and rising POCUS penetration positions Asia-Pacific as the principal source of incremental growth over the forecast period.
Ultrasound Needle Guides Regional Commentary
- North America
North America accounted for 36% of the global Ultrasound Needle Guides market revenue in 2025. The United States dominates on the strength of its interventional-radiology infrastructure, POCUS adoption, FDA regulatory clarity, and proximity to leading accessory manufacturers, while growing transperineal prostate biopsy adoption and expanding point-of-care ultrasound use across emergency and critical care reinforce its leadership.
- Europe
Europe is a large and advanced regional market, supported by well-established interventional-radiology and anesthesiology practice, harmonized CE-marking regulatory pathways, and strong clinical adoption of ultrasound-guided regional anesthesia. Product launches and platform-embedded guidance software from Siemens Healthineers and Esaote, alongside distribution reach from CIVCO and Rocket Medical, reinforce the region's role in supplying both hospital and ambulatory procedure settings across Germany, France, the United Kingdom, Italy, and Spain.
- Asia-Pacific
Asia-Pacific is the fastest-growing region, propelled by rising cancer incidence, rapid hospital and diagnostic imaging infrastructure build-out, and growing healthcare investment across China, Japan, India, South Korea, and Australia. China's expanding installed ultrasound base, Japan's POCUS adoption, India's low-cost diagnostic imaging scale-up, and growing regional manufacturing by Mindray are accelerating regional guide consumption and clinical-training activity.
- Rest of World
The Rest of World region, spanning Latin America, the Middle East, and Africa, is an emerging growth frontier. Expanding hospital and diagnostic imaging infrastructure, rising demand for image-guided biopsy and anesthesia procedures, and gradual alignment of regulatory frameworks with international standards are broadening access, while distributor partnerships with global manufacturers support the build-out of regional procedure capacity.
Ultrasound Needle Guides Market Competitive Landscape
The Ultrasound Needle Guides market is classified as Fragmented. A group of specialized accessory manufacturers with broad probe-compatible portfolios, including CIVCO Medical Solutions, Aspen Surgical, and Argon Medical Devices, hold leading positions through extensive OEM-compatible product lines, while diversified ultrasound system OEMs, including GE HealthCare, Siemens Healthineers, Mindray, and Esaote, compete by embedding guidance and tracking capability directly into their imaging platforms.
Focused device makers such as Geotek Medical, Rocket Medical, Becton, Dickinson and Company (BD), and Veran Medical Technologies compete through specialized bracket systems, vascular-access integration, and electromagnetic tracking expertise, respectively, intensifying competition across both the commodity disposable and premium tracking-enabled segments.
The Ultrasound Needle Guides Competitive Landscape can be evaluated across the following dimensions:
- Market concentration: Fragmented, with broad-portfolio accessory specialists leading and diversified ultrasound OEMs competing through platform-embedded guidance.
- Leading players: CIVCO Medical Solutions, Aspen Surgical, and Argon Medical Devices anchor the top tier through extensive probe-compatible product lines.
- Geographic reach: Leaders operate broad distribution networks spanning hospitals, ASCs, and diagnostic imaging centers across North America, Europe, and Asia-Pacific.
- Product portfolio strength: Top players offer reusable brackets, disposable inserts, sterile procedure kits, and increasingly, tracking-enabled and AI-assisted guidance accessories.
- Platform integration: Ownership of or partnership access to major ultrasound imaging platforms, including GE HealthCare's and Siemens Healthineers' embedded guidance software, is a decisive advantage.
- Strategic partnerships: Tie-ups between OEMs and robotics or navigation specialists, such as GE HealthCare's collaboration with Medtronic on robotic-assisted needle guidance, extend reach.
- M&A activity: Selective consolidation, including Siemens Healthineers' acquisition of a niche needle-tracking technology firm, is reshaping the tracking-enabled premium segment.
- Manufacturing capabilities: Probe-specific tooling, sterile single-use manufacturing at scale, and integration with electromagnetic and AI-based tracking software are key competitive moats.
- Innovation focus: AI-assisted trajectory mapping, adjustable multi-angle mechanisms, electromagnetic needle-tip tracking, and reduced-plastic sustainable packaging.
Ultrasound Needle Guides Market Recent Developmental Activities
- In 2026, CIVCO Medical Solutions expanded its TP Pivot Pro transperineal biopsy guide portfolio and continued rollout of the Verza and VerzaLink multi-angle needle guidance systems across additional ultrasound transducer families. Strategic significance: Broadens freehand, infection-reducing transperineal biopsy access and reinforces CIVCO's position as the leading probe-compatible accessory provider.
- In 2026, Siemens Healthineers acquired a niche needle-tracking technology firm to embed AI-assisted trajectory-mapping software into its Acuson ultrasound platform. Strategic significance: Strengthens platform-embedded guidance capability and extends Siemens Healthineers' premium, tracking-enabled offering.
- In 2025, GE HealthCare deepened its collaboration with Medtronic to integrate needle-guidance modules into robotic-assisted ultrasound platforms. Strategic significance: Expands GE HealthCare's addressable procedures into robotic-assisted interventions and reinforces platform differentiation.
- In 2025, Becton, Dickinson and Company (BD) advanced adoption of its SiteRite ultrasound system with the integrated Cue Needle Tracking System, providing continuous real-time needle tracking for vascular access procedures. Strategic significance: Reinforces BD's leadership in vascular-access guidance and extends tracking-enabled functionality into high-volume bedside procedures.
- In 2025, Mindray introduced its Resona A20 point-of-care ultrasound platform with expanded biopsy and needle-guidance accessory compatibility. Strategic significance: Strengthens Mindray's position in the fast-growing Asia-Pacific point-of-care ultrasound and guided-procedure segment.
- In 2025, Argon Medical Devices expanded its biopsy device and needle-guidance accessory portfolio to support a broader range of ultrasound transducer configurations. Strategic significance: Extends Argon Medical Devices' reach across hospital and ambulatory surgical center biopsy procedures.
- In 2025, Esaote bundled needle-guidance accessories with new interventional point-of-care ultrasound platform launches across Europe. Strategic significance: Strengthens Esaote's regional distribution and accessory attach rate on newly placed imaging systems.
- In 2024, Rocket Medical launched an expanded range of aspiration and needle-guidance accessories for regional anesthesia and pain-management procedures. Strategic significance: Broadens Rocket Medical's presence in the fast-growing anesthesia and nerve block application segment.
- In 2024, Geotek Medical expanded its reusable needle guide bracket portfolio for compatibility with additional major ultrasound transducer families. Strategic significance: Strengthens Geotek Medical's position in the reusable, probe-specific bracket category.
- In 2024, Aspen Surgical expanded its sterile procedure kit packaging to bundle disposable needle guides with anesthesia and vascular-access trays. Strategic significance: Reinforces Aspen Surgical's channel strength in ambulatory surgical centers and sterile-kitting workflows.
- In 2023, Veran Medical Technologies continued development of its electromagnetic navigation platform, informing fusion and tracking roadmaps for ultrasound-guided needle placement. Strategic significance: Supports the broader industry shift toward tracking-enabled, navigation-assisted needle guidance.
Ultrasound Needle Guides Market Segmentation
Ultrasound Needle Guides Market by Product Type
- Reusable Ultrasound Needle Guides
- Disposable Ultrasound Needle Guides
- Sterile Ultrasound Needle Guides
- Non-Sterile Ultrasound Needle Guides
Ultrasound Needle Guides Market by Needle Guidance Mechanism
- In-Plane Needle Guides
- Out-of-Plane Needle Guides
- Adjustable-Angle Needle Guides
- Fixed-Angle Needle Guides
Ultrasound Needle Guides Market by Application
- Anesthesia & Nerve Blocks
- Biopsy Procedures
- Aspiration Procedures
- Pain Management
- Others
Ultrasound Needle Guides Market by End-Users
- Hospitals & Clinics
- Ambulatory Surgical Centers (ASCs)
- Diagnostic Imaging Centers
- Others
Ultrasound Needle Guides Market by Geography
-
North America Ultrasound Needle Guides Market
- United States Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Canada Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Mexico Ultrasound Needle Guides Market Size in USD million (2023-2034)
-
Europe Ultrasound Needle Guides Market
- Germany Ultrasound Needle Guides Market Size in USD million (2023-2034)
- United Kingdom Ultrasound Needle Guides Market Size in USD million (2023-2034)
- France Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Italy Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Spain Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Rest of Europe Ultrasound Needle Guides Market Size in USD million (2023-2034)
-
Asia-Pacific Ultrasound Needle Guides Market
- China Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Japan Ultrasound Needle Guides Market Size in USD million (2023-2034)
- India Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Australia Ultrasound Needle Guides Market Size in USD million (2023-2034)
- South Korea Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Rest of Asia-Pacific Ultrasound Needle Guides Market Size in USD million (2023-2034)
-
Rest of the World (RoW) Ultrasound Needle Guides Market
- Middle East Ultrasound Needle Guides Market Size in USD million (2023-2034)
- Africa Ultrasound Needle Guides Market Size in USD million (2023-2034)
- South America Ultrasound Needle Guides Market Size in USD million (2023-2034)
Ultrasound Needle Guides Market Recent Industry Trends and Milestones (2023-2026)
|
Category |
Key Developments |
|
Ultrasound Needle Guides Market Product Approval |
Regulatory clearances continue to expand the addressable procedure base. CIVCO Medical Solutions received FDA 510(k) clearance for its TP Pivot Pro transperineal biopsy guide, supporting freehand, infection-reducing transperineal prostate biopsy pathways, while BD's SiteRite 9 ultrasound platform, cleared with the integrated Cue Needle Tracking System, extends continuous real-time needle tracking for vascular access. Additional 510(k) clearances for multi-angle and probe-specific guides from Argon Medical Devices, Rocket Medical, and Geotek Medical are broadening compatibility across the installed base of hospital ultrasound systems and creating durable, recurring demand for compliant single-use accessories. |
|
Ultrasound Needle Guides Market Expansion |
Manufacturers broadened probe-specific coverage and clinical training infrastructure. CIVCO expanded its Ultra-Pro II and Verza/VerzaLink portfolios across additional GE HealthCare, Siemens Healthineers, and Mindray transducer families, and scaled hands-on transperineal biopsy simulation workshops. Esaote and Mindray bundled needle-guidance accessories with new point-of-care ultrasound platform launches, while Aspen Surgical expanded sterile procedure-kit packaging to bundle disposable guides with anesthesia and vascular-access trays for ambulatory surgical centers. |
|
Ultrasound Needle Guides Market Investment |
Strategic investment concentrated on tracking-enabled and AI-assisted guidance. Siemens Healthineers acquired a niche needle-tracking technology firm to embed trajectory-mapping software into its Acuson platform, and GE HealthCare deepened a partnership with Medtronic to integrate needle-guidance modules into robotic-assisted platforms. Veran Medical Technologies' electromagnetic navigation assets continued to inform fusion and tracking roadmaps across the sector, reinforcing capital flow toward tracking-enabled and reusable premium guide categories alongside continued volume growth in disposable guides. |
|
Company Strategy |
CIVCO Medical Solutions: Broadest probe-compatible portfolio and transperineal prostate leadership. Becton, Dickinson and Company (BD): Vascular-access and tracking-system integration. GE HealthCare and Siemens Healthineers: Platform-embedded guidance and robotic integration. Mindray and Esaote: Bundled point-of-care ultrasound and accessory strategy. Aspen Surgical: Sterile kitting and ASC channel strength. Geotek Medical, Rocket Medical, and Argon Medical Devices: Specialized reusable bracket systems and biopsy-adjacent device portfolios. Veran Medical Technologies: Electromagnetic tracking and navigation expertise. |
|
Emerging Technologies |
AI-assisted trajectory mapping, adjustable multi-angle guide mechanisms, and electromagnetic needle-tip tracking fused with ultrasound imaging are the leading edge of innovation. Point-of-care ultrasound (POCUS) expansion into critical care and outpatient settings is broadening the addressable base for compact, disposable guides, while robotic-assisted and navigation-integrated platforms are emerging for prostate and liver interventions. Sustainability initiatives, including reduced-plastic disposable packaging and clinician training and simulation programs, are expanding alongside these technology shifts. |
Ultrasound Needle Guides Market Startup Funding and Investment Trends
Investment in the Ultrasound Needle Guides ecosystem has concentrated on tracking-enabled guidance, AI-assisted trajectory mapping, and expanded probe compatibility. The following companies illustrate recent funding and investment activity and technology focus.
|
Company |
Total Funding |
Funding Stage |
Main Offering |
Core Technology |
|
Veran Medical Technologies |
Undisclosed (strategic acquisition) |
Acquired / Strategic |
Electromagnetic navigation guides |
EMT-fused ultrasound tracking |
|
Request for unlocking the report of the @ Ultrasound Needle Guides Market | ||||
Capital is flowing toward providers that combine broad probe compatibility with tracking and software differentiation. Siemens Healthineers' acquisition of a niche needle-tracking technology firm and GE HealthCare's collaboration with Medtronic on robotic-assisted guidance integration underscore the strategic value of tracking-enabled needle guidance infrastructure.
Specialized manufacturers such as Geotek Medical and Rocket Medical continue to scale probe-specific bracket and accessory portfolios, while Veran Medical Technologies' electromagnetic navigation expertise continues to inform fusion and tracking roadmaps across the sector. Collectively, these investments signal conviction that platform integration, tracking capability, and probe-specific breadth will define the next phase of competitive advantage in the global Ultrasound Needle Guides market.
Key Takeaways from the Ultrasound Needle Guides Market Report Study
- Market size analysis for the current ultrasound needle guides market size (2025) and market forecast for 9 years (2026 to 2034).
- Top key product/technology developments, mergers, acquisitions, partnerships, and joint ventures that happened over the last 3 years.
- Key companies dominating the global ultrasound needle guides market.
- Various opportunities available for competitors in the ultrasound needle guides market space.
- What are the top-performing segments in 2025? How will these segments perform in 2034?
- Which are the top-performing regions and countries in the current ultrasound needle guides market scenario?
- Which are the regions and countries where companies should concentrate their opportunities for ultrasound needle guides market growth in the future?
Target audience who can benefit from this ultrasound needle guides market report study
- Ultrasound needle guides product providers
- Research organizations and consulting companies
- Neurodegenerative disease therapeutics-related organizations, associations, forums, and other alliances
- Government and corporate offices
- Start-up companies, venture capitalists, and private equity firms
- Distributors and traders dealing in ultrasound needle guides
- Various end-users who want to know more about the ultrasound needle guides market and the latest technological developments in the ultrasound needle guides market.
Stay updated with us for Recent Articles @ New DelveInsight Blogs