Neuroprosthetics Market Summary
- The Neuroprosthetics market is estimated at USD 8.05 billion in 2025 and is projected to reach USD 23.7 billion by 2034. Growth is anchored in the rising burden of neurological and sensory disorders, the expanding use of neurostimulation and sensory restoration, and rapid innovation in brain-computer interfaces and implantable neurotechnology.
- The global Neuroprosthetics market is growing at a CAGR of 12.75% during the forecast period from 2026 to 2034.
- By type, the auditory prosthetics segment dominated the Neuroprosthetics market with a 45% share in 2025.
- By procedure, the invasive segment dominated the Neuroprosthetics market with a share of 72% in 2025.
- By technology, the spinal cord stimulation segment dominated the Neuroprosthetics market with a share of 30% in 2025.
- By end-user, the hospitals and clinics segment dominated the Neuroprosthetics market with a share of 68% in 2025.
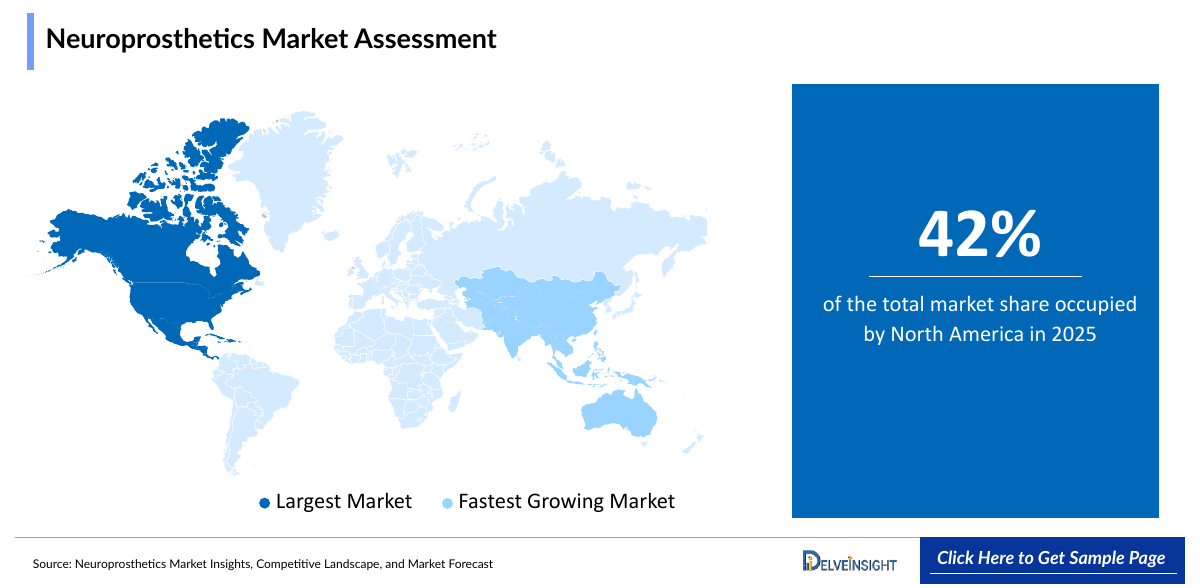
- North America dominated the global Neuroprosthetics market revenue with a share of 42% in 2025, representing the highest regional market share globally.
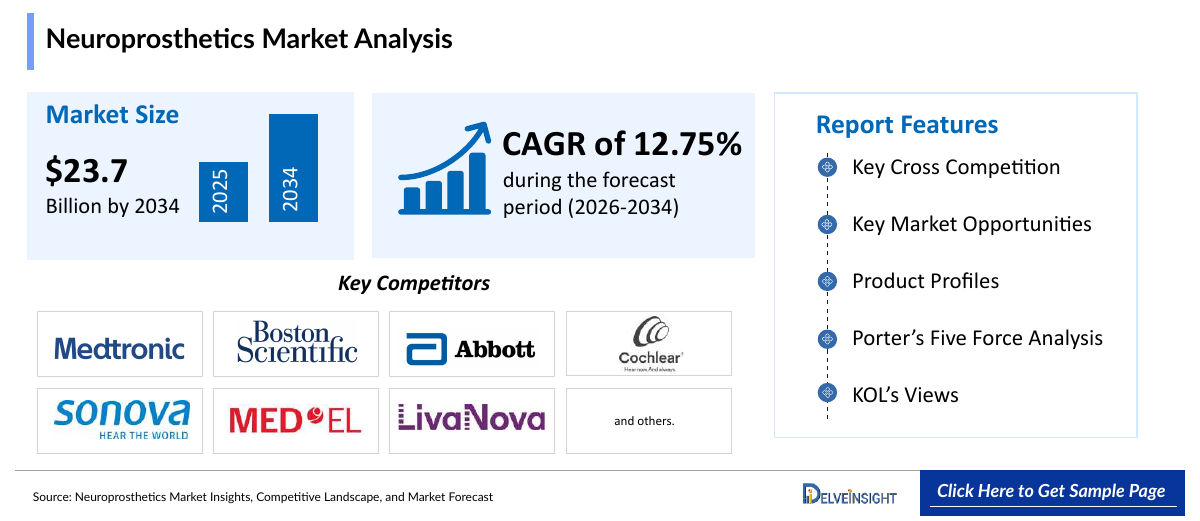
Neuroprosthetics are devices that interface with the nervous system to restore or augment sensory, motor, or cognitive function lost to injury, disease, or congenital conditions. The category spans motor prosthetics and brain-computer interfaces that restore movement and control; cognitive prosthetics; auditory prosthetics, principally cochlear implants and auditory brainstem implants; and visual prosthetics such as retinal implants. Neuroprosthetic function is delivered through neurostimulation and interface technologies including deep brain stimulation, vagus nerve stimulation, sacral nerve stimulation, spinal cord stimulation, transcranial magnetic stimulation, and others, by invasive and non-invasive means. These devices are supplied by leading neurotechnology companies including Medtronic, Boston Scientific, and Abbott in neurostimulation; Cochlear, Sonova, MED-EL, and Demant in auditory prosthetics; LivaNova in vagus nerve stimulation; Nevro in spinal cord stimulation; NeuroPace in responsive neurostimulation; and emerging brain-computer interface developers such as Blackrock Neurotech and Synchron. Neuroprosthetics are used across hearing loss, Parkinson's disease, epilepsy, chronic pain, paralysis, and other neurological and sensory conditions, predominantly in hospitals and clinics. Over the past decade, the field has advanced with closed-loop and responsive neurostimulation, rechargeable and smaller implants, and rapid progress in brain-computer interfaces. Driven by the rising burden of neurological and sensory disorders and rapid neurotechnology innovation, neuroprosthetics is a dynamic and fast-growing segment of the medical device market.
Neuroprosthetics Market Key Growth Drivers
- The rising global burden of neurological disorders, including Parkinson's disease, epilepsy, and chronic pain, is expanding demand for neurostimulation and neuroprosthetic therapy.
- The high and rising prevalence of hearing loss and sensory disorders is driving demand for cochlear implants and other sensory neuroprosthetics.
- Rapid innovation in brain-computer interfaces and implantable neurotechnology is opening new applications in paralysis and motor restoration.
- Technological advances, including closed-loop and responsive neurostimulation, rechargeable and smaller implants, and improved electrodes, are improving outcomes and adoption.
- The aging population and rising incidence of neurological and sensory conditions are increasing the treated population.
- Expanding reimbursement, awareness, and access to neuroprosthetic therapies are broadening the global market.
- The convergence of rising neurological and sensory disease burden, neurostimulation expansion, and brain-computer interface innovation is expected to sustain strong growth in the global Neuroprosthetics market through 2034.
Key Companies in Neuroprosthetics Market
The competitive landscape is led by the following active developers and manufacturers of neuroprosthetic devices:
- Medtronic plc
- Boston Scientific Corporation
- Abbott Laboratories
- Cochlear Limited
- Sonova Holding AG
- MED-EL Medical Electronics
- LivaNova PLC
- NEVRO CORP.
- NeuroPace, Inc.
- Blackrock Neurotech
For illustrative purposes, only the top 10 companies are listed in the Table of Contents. The report may include analysis and references to additional companies relevant to the market assessment.
Neuroprosthetics Market Size
The following snapshot summarizes the principal report metrics for the Neuroprosthetics market.
|
Report Metrics |
Details |
|
2025 Market Size |
USD 8.05 billion |
|
2034 Projected Market Size |
USD 23.7 billion |
|
Growth Rate (2026-2034) |
12.75% CAGR |
|
Largest Market |
North America |
|
Fastest Growing Market |
Asia-Pacific |
|
Market Structure |
Consolidated |
All market values are expressed in USD and represent DelveInsight estimates synthesized from primary and secondary research.
Factors Contributing to the Growth of the Neuroprosthetics Market
Market Drivers
Rising Burden of Neurological Disorders
The rising global burden of neurological disorders is the foundational driver of the neuroprosthetics market. Conditions such as Parkinson's disease, essential tremor, epilepsy, chronic pain, and the consequences of stroke and spinal cord injury affect large and growing populations, and neurostimulation and neuroprosthetic therapies are central to their management. Deep brain stimulation for movement disorders, responsive and vagus nerve stimulation for epilepsy, and spinal cord stimulation for chronic pain are established therapies delivered by neuroprosthetic devices, and the rising prevalence of these conditions with aging expands the treated population. The growth of neurological disease worldwide, together with the increasing adoption of device-based therapy for patients inadequately controlled by medication, drives demand. As the burden of neurological disorders continues to rise, demand for neuroprosthetic therapy continues to grow, reinforcing sustained market growth throughout the forecast period.
Rising Prevalence of Hearing Loss and Sensory Disorders
The high and rising prevalence of hearing loss and sensory disorders is a powerful driver of the neuroprosthetics market. Hearing loss affects a very large and growing global population, driven by aging, noise exposure, and other factors, and cochlear implants and auditory brainstem implants restore hearing for patients with severe to profound hearing loss who do not benefit from hearing aids. Cochlear implants, supplied by Cochlear, Sonova, MED-EL, and Demant, represent the largest and most established neuroprosthetic application, and rising diagnosis, expanding candidacy, and growing adoption, including among adults and older patients, expand demand. Visual prosthetics for retinal and other vision disorders represent an emerging sensory application. As the prevalence of hearing loss and sensory disorders rises and adoption of sensory neuroprosthetics grows, this trend is expected to be a leading driver of market growth across the forecast period.
Rapid Innovation in Brain-Computer Interfaces
Rapid innovation in brain-computer interfaces and implantable neurotechnology is a defining driver and opportunity in the neuroprosthetics market. Brain-computer interfaces, which decode neural activity to restore communication and movement for patients with paralysis, amyotrophic lateral sclerosis, and other conditions, have advanced rapidly, with companies such as Blackrock Neurotech, Synchron, and others progressing through clinical studies and achieving significant milestones. Motor neuroprosthetics and brain-computer interfaces represent a frontier with large potential to restore function for severely disabled patients. Substantial investment and high-profile entrants have accelerated progress and visibility. While largely investigational, these technologies are advancing toward clinical use and represent a major long-term growth driver. As brain-computer interface and motor neuroprosthetic technology continues to advance toward clinical application, this innovation is expected to be an important driver of neuroprosthetics market growth and transformation across the forecast period.
Technological Advancement in Neurostimulation
Continuous technological innovation in neurostimulation and neuroprosthetic devices is improving outcomes and driving market growth. Closed-loop and responsive neurostimulation systems, exemplified by NeuroPace's responsive neurostimulation for epilepsy and adaptive deep brain stimulation, adjust therapy based on neural signals to improve efficacy. Rechargeable, smaller, and magnetic resonance-conditional implants improve convenience and patient experience, and advances in electrodes, leads, and signal processing enhance performance across neurostimulation and sensory prosthetics. Improved cochlear implant processors and electrode arrays enhance hearing outcomes. These innovations expand applications, improve outcomes, and differentiate products, supporting adoption and premium pricing. As neurostimulation and neuroprosthetic technology continues to advance across closed-loop systems, implant design, and sensory processing, technological innovation is expected to be a significant driver of market growth across the forecast period.
Aging Population and Rising Incidence of Neurological and Sensory Conditions
The aging global population and rising incidence of neurological and sensory conditions are powerful drivers of neuroprosthetic demand. Older adults carry a substantially higher prevalence of Parkinson's disease, essential tremor, chronic pain, and age-related hearing loss, and the number of people aged 60 and older is rising rapidly worldwide, directly expanding the population requiring neuroprosthetic therapy. The growing burden of neurological disease and hearing loss in aging populations increases demand for deep brain stimulation, spinal cord stimulation, and cochlear implants. The chronic nature of these conditions and the long-term use of implanted devices generate sustained demand. As populations age and the incidence of neurological and sensory conditions rises, demographic trends are expected to be a significant driver of neuroprosthetic demand across the forecast period.
Expanding Reimbursement, Awareness, and Access
Expanding reimbursement, awareness, and access to neuroprosthetic therapies are substantial drivers of the market. Growing recognition of the clinical value of neurostimulation and cochlear implants, together with expanding reimbursement and candidacy criteria, is increasing adoption, and patient and physician awareness of device-based therapies for neurological and sensory conditions continues to grow. The expansion of cochlear implant programs, neurostimulation centers, and specialist capacity broadens access, and growing healthcare investment in emerging markets expands the treated population. Both multinational and emerging companies are expanding their presence and access programs. As reimbursement, awareness, and access continue to expand, these factors are expected to be an important driver of neuroprosthetics market growth across the forecast period, particularly in underpenetrated regions and applications.
Market Restraints
Despite strong momentum, the Neuroprosthetics market faces material constraints. The very high cost of neuroprosthetic devices and implantation procedures, together with the need for specialized surgical and programming infrastructure, limits adoption, particularly in resource-limited settings. Reimbursement, while expanding, remains variable across regions and applications and can constrain access, particularly for newer and investigational technologies. The invasive nature of many neuroprosthetics carries surgical and device-related risks, including infection, lead and hardware complications, and the need for revisions, requiring careful patient selection and specialist expertise. Many advanced applications, particularly brain-computer interfaces and motor neuroprosthetics, remain largely investigational, with long and costly development and regulatory pathways and uncertain timelines to broad clinical use. A shortage of trained specialists, including neurosurgeons, neurologists, and audiologists, and limited access to specialized centers constrain capacity. Rigorous and evolving regulatory requirements for implantable neurological devices, including Food and Drug Administration pathways and the European Medical Device Regulation, add cost and complexity. Finally, uneven infrastructure, limited awareness, and affordability constraints in emerging markets can restrict adoption across parts of the forecast period, even as these markets offer growth potential.
Neuroprosthetics Market Segment Analysis
The Neuroprosthetics Market is segmented by Type (Auditory Prosthetics, Motor Prosthetics, Visual Prosthetics, Cognitive Prosthetics), Procedure (Invasive, Non-Invasive), Technology (Spinal Cord Stimulation, Deep Brain Stimulation, Vagus Nerve Stimulation, Sacral Nerve Stimulation, Transcranial Magnetic Stimulation, Others), End-User (Hospitals and Clinics, Ambulatory Surgical Centers, Others), and Geography (North America, Europe, Asia-Pacific, Rest of World).
By Type
Dominant Subsegment: Auditory Prosthetics.
The auditory prosthetics segment accounted for 45% of the Neuroprosthetics market in 2025. Auditory prosthetics, principally cochlear implants and auditory brainstem implants, dominate because they are the largest, most established, and most widely adopted neuroprosthetic application, restoring hearing for large numbers of patients with severe to profound hearing loss. Cochlear implants from Cochlear, Sonova, MED-EL, and Demant have decades of clinical use, broad reimbursement, and expanding candidacy, including growing adoption among adults and older patients, and the high prevalence of hearing loss drives the largest share of the market. Motor prosthetics, including brain-computer interfaces that restore movement and control for patients with paralysis, represent a rapidly advancing and high-potential segment led by companies such as Blackrock Neurotech and Synchron, though largely investigational. Visual prosthetics, such as retinal implants, represent an emerging sensory application, and cognitive prosthetics are a developing area. Nonetheless, the scale, maturity, and broad adoption of auditory prosthetics secure the leadership of this segment across the forecast period, with motor prosthetics and brain-computer interfaces representing the fastest-growing frontier.
By Procedure
Dominant Subsegment: Invasive.
The invasive segment accounted for 72% of the Neuroprosthetics market in 2025. Invasive procedures dominate because the majority of neuroprosthetic devices, including cochlear implants, deep brain stimulation, spinal cord stimulation, vagus nerve stimulation, responsive neurostimulation, and implantable brain-computer interfaces, are surgically implanted to directly interface with the nervous system. The high value of implanted devices, their established efficacy, and the clinical requirement for direct neural interface drive the overwhelming share of the market. Invasive neuroprosthetics deliver targeted, durable therapy and represent the core of the established market. The non-invasive segment, including transcranial magnetic stimulation and non-invasive stimulation and interface approaches, is a smaller but growing segment that avoids surgical risk and is used in specific applications such as depression and certain neurological conditions, and non-invasive brain-computer interfaces are an area of development. Nonetheless, the dominance of implanted devices across the major neuroprosthetic applications secures the leadership of the invasive segment across the forecast period, with non-invasive approaches growing in specific areas.
By Technology
Dominant Subsegment: Spinal Cord Stimulation.
The spinal cord stimulation segment accounted for 30% of the Neuroprosthetics market in 2025. Spinal cord stimulation dominates among neurostimulation technologies because it is the largest neurostimulation application by revenue, used to treat chronic pain, including failed back surgery syndrome and other conditions, and supplied by major players including Medtronic, Boston Scientific, Abbott, and Nevro. The large population with chronic pain, the established efficacy and reimbursement of spinal cord stimulation, and continued innovation in waveforms and closed-loop systems drive the largest share of neurostimulation technology revenue. Deep brain stimulation, used for Parkinson's disease, essential tremor, and other conditions, is a large and established technology led by Medtronic, Boston Scientific, and Abbott, and vagus nerve stimulation, led by LivaNova, is used for epilepsy and depression. Sacral nerve stimulation serves bladder and bowel conditions, transcranial magnetic stimulation serves non-invasive applications, and responsive neurostimulation serves epilepsy. Nonetheless, the scale, established use, and ongoing innovation of spinal cord stimulation secure the leadership of this segment across the forecast period, with deep brain stimulation and other technologies contributing substantially.
By End-User
Dominant Subsegment: Hospitals and Clinics.
The hospitals and clinics segment accounted for 68% of the Neuroprosthetics market in 2025. Hospitals and clinics dominate because neuroprosthetic implantation, including deep brain stimulation, spinal cord stimulation, cochlear implantation, and other procedures, requires specialized surgical, imaging, and programming infrastructure and multidisciplinary expertise concentrated in hospitals and specialized clinics. The majority of neuroprosthetic procedures, device programming, and follow-up occur in hospitals and specialist centers, driving the largest share of device use, and hospitals are the primary purchasers of high-value neuroprosthetic systems. Cochlear implant programs, neurosurgery and neurology centers, and pain clinics are concentrated in these settings. Ambulatory surgical centers represent a smaller but growing end user as selected procedures shift to outpatient settings, and other settings, including rehabilitation and research centers, add further demand, with research centers important for brain-computer interface development. Nonetheless, the concentration of specialized implantation and management in hospitals and clinics secures the leadership of this segment across the forecast period, with ambulatory centers growing modestly.
Neuroprosthetics Market Region Analysis
North America accounted for 42% of the global Neuroprosthetics market revenue in 2025, representing the highest regional market share globally. The region's dominance reflects advanced neurological and surgical infrastructure, high adoption of neurostimulation and cochlear implants, strong reimbursement, substantial investment in neurotechnology, and the presence of leading manufacturers. The United States leads on the strength of broad adoption of deep brain stimulation, spinal cord stimulation, and cochlear implants, high healthcare spending, leadership in brain-computer interface development and investment, and the presence of major players including Medtronic, Boston Scientific, Abbott, NeuroPace, Nevro, and emerging brain-computer interface companies. Disease burden is substantial, with large populations affected by neurological disorders, chronic pain, and hearing loss. The regulatory environment is well established, with the Food and Drug Administration providing pathways, including breakthrough device designations for novel neurotechnologies, and a track record of approving neuroprosthetic devices. Strong research infrastructure and venture investment further reinforce the market. This combination of infrastructure, adoption, and innovation reinforces North America's leadership in the global market.
Fastest Growing Region: Asia-Pacific
Asia-Pacific is the fastest-growing region in the Neuroprosthetics market. The region's elevated CAGR is driven by large populations, a rising burden of neurological disorders and hearing loss, expanding healthcare access, and growing neurosurgical and cochlear implant capacity across China, Japan, India, South Korea, and Southeast Asia. Rising prevalence of neurological disease and hearing loss, aging populations in several countries, and increasing diagnosis and treatment expand demand, and growing healthcare investment and insurance coverage are improving access to high-cost neuroprosthetic therapies. China and other countries are expanding cochlear implant programs and neurostimulation capacity and developing domestic neurotechnology, and rising awareness increases adoption. Both multinational and regional manufacturers are expanding their presence. Government programs supporting hearing and neurological care further support growth. The combination of large populations, rising disease burden, expanding access, and growing capacity positions Asia-Pacific as the highest-growth region over the forecast period.
Regional Commentary
North America
North America accounted for 42% of the global Neuroprosthetics market revenue in 2025. The United States dominates the region on the strength of advanced infrastructure, high adoption of neurostimulation and cochlear implants, leadership in brain-computer interface development, and the presence of leading manufacturers, while Canada contributes through its healthcare system and Mexico expands access within its growing healthcare sector.
Europe
Europe represents the second-largest regional market, led by Germany, France, and the United Kingdom. Growth is supported by established neurological and cochlear implant care, strong reimbursement, and the presence of major manufacturers such as Sonova, MED-EL, LivaNova, and Demant, while the European Medical Device Regulation shapes product requirements and market access across the region.
Asia-Pacific
Asia-Pacific is the fastest-growing region, propelled by large populations, a rising burden of neurological disorders and hearing loss, expanding healthcare access, and growing neurosurgical and cochlear implant capacity across China, Japan, India, South Korea, and Southeast Asia. Expanding programs, domestic neurotechnology, and growing access are broadening adoption.
Rest of World
The Rest of World region, spanning the Middle East, Africa, and South America, is an emerging growth frontier. A rising burden of neurological and sensory disorders, improving neurosurgical and cochlear implant capacity, and expanding access are broadening adoption from a developing base, while investment in specialized care supports growth.
Neuroprosthetics Market Competitive Landscape
The Neuroprosthetics market is classified as Consolidated. A group of large neurotechnology and medical device companies holds the majority of revenue, led by Medtronic, Boston Scientific, and Abbott in neurostimulation and Cochlear, Sonova, MED-EL, and Demant in auditory prosthetics, with LivaNova, Nevro, and NeuroPace holding significant positions, while emerging brain-computer interface developers such as Blackrock Neurotech and Synchron and a growing field of innovators compete at the frontier.
The competitive landscape can be evaluated across the following dimensions:
- Market concentration: Consolidated, with established neurostimulation and auditory prosthetic segments led by a few large companies alongside emerging brain-computer interface innovators.
- Leading players: Medtronic, Boston Scientific, and Abbott lead neurostimulation; Cochlear, Sonova, MED-EL, and Demant lead auditory prosthetics, and LivaNova, Nevro, NeuroPace, Blackrock Neurotech, and Synchron hold significant or emerging positions.
- Geographic reach: Leaders operate global commercial and manufacturing networks, with strong positions across North America, Europe, and Asia-Pacific.
- Product portfolio strength: Players hold portfolios spanning deep brain, spinal cord, vagus nerve, and responsive stimulation, cochlear implants, and emerging brain-computer interfaces.
- Pipeline strength: Deep pipelines in closed-loop and adaptive neurostimulation, next-generation cochlear implants, and brain-computer interfaces.
- Strategic partnerships: Collaborations with research institutions and clinical centers, and significant venture investment in brain-computer interfaces, shape the competitive landscape.
- M&A activity: Consolidation and acquisitions continue, and significant investment flows into emerging neurotechnology companies.
- Manufacturing capabilities: Specialized implantable device manufacturing and quality systems are key competitive strengths and barriers to entry.
- Innovation focus: Closed-loop and adaptive neurostimulation, next-generation cochlear implants, brain-computer interfaces, and novel electrodes and interfaces.
Neuroprosthetics Market Recent Developmental Activities
In 2023 and 2024, Medtronic advanced adaptive and closed-loop deep brain stimulation and expanded its neurostimulation portfolio. Strategic significance: Advances responsive, personalized neurostimulation and reinforces Medtronic's leadership.
In 2023 and 2024, Boston Scientific and Abbott expanded their deep brain and spinal cord stimulation portfolios, including new waveforms and closed-loop systems. Strategic significance: Strengthens competition and advances neurostimulation technology.
In 2023 and 2024, Cochlear, Sonova, MED-EL, and Demant advanced next-generation cochlear implant systems and sound processors. Strategic significance: Improves hearing outcomes and sustains leadership in the largest neuroprosthetic segment.
In 2023 and 2024, Synchron advanced its endovascular brain-computer interface through clinical studies, and Blackrock Neurotech advanced its implantable brain-computer interface technology. Strategic significance: Advances brain-computer interfaces toward clinical use and attracts significant attention and investment.
In 2023 and 2024, high-profile brain-computer interface entrants and substantial venture investment accelerated progress and visibility in motor neuroprosthetics. Strategic significance: Raises the profile and long-term potential of the brain-computer interface frontier.
In 2023 and 2024, NeuroPace advanced its responsive neurostimulation system for epilepsy. Strategic significance: Advances closed-loop neurostimulation and personalized epilepsy therapy.
In 2023 and 2024, Nevro and others advanced spinal cord stimulation technology for chronic pain, including new indications such as painful diabetic neuropathy. Strategic significance: Expands the applications and addressable population for spinal cord stimulation.
In 2023 and 2024, the FDA granted breakthrough device designations to several novel neurotechnologies, including brain-computer interfaces. Strategic significance: Supports and accelerates the development of innovative neuroprosthetics.
In 2023 and 2024, research advanced in restoring movement, communication, and sensation for patients with paralysis using brain-computer interfaces and neural interfaces. Strategic significance: Demonstrates the transformative potential of motor neuroprosthetics.
In 2023 and 2024, rechargeable, smaller, and magnetic resonance-conditional neurostimulation implants expanded across manufacturers. Strategic significance: Improves patient experience and convenience and supports adoption.
In 2023 and 2024, cochlear implant candidacy and programs expanded, including among adults and older patients. Strategic significance: Broadens the addressable population for auditory prosthetics.
In 2023 and 2024, the European Medical Device Regulation continued to reshape requirements and market access for implantable neurological devices in Europe. Strategic significance: Raises compliance requirements and influences portfolio and market-entry strategies.
Neuroprosthetics Market Segmentation
Neuroprosthetics Market by Type
- Auditory Prosthetics (Cochlear and Auditory Brainstem Implants)
- Motor Prosthetics and Brain-Computer Interfaces
- Visual Prosthetics (Retinal Implants)
- Cognitive Prosthetics
Neuroprosthetics Market by Procedure
- Invasive
- Non-Invasive
Neuroprosthetics Market by Technology
- Spinal Cord Stimulation
- Deep Brain Stimulation
- Vagus Nerve Stimulation
- Sacral Nerve Stimulation
- Transcranial Magnetic Stimulation
- Others
Neuroprosthetics Market by End-User
- Hospitals and Clinics
- Ambulatory Surgical Centers
- Others
Neuroprosthetics Market by Geography
- North America Neuroprosthetics Market
- United States Neuroprosthetics Market Size in USD million (2023-2034)
- Canada Neuroprosthetics Market Size in USD million (2023-2034)
- Mexico Neuroprosthetics Market Size in USD million (2023-2034)
- Europe Neuroprosthetics Market
- Germany Neuroprosthetics Market Size in USD million (2023-2034)
- United Kingdom Neuroprosthetics Market Size in USD million (2023-2034)
- France Neuroprosthetics Market Size in USD million (2023-2034)
- Italy Neuroprosthetics Market Size in USD million (2023-2034)
- Spain Neuroprosthetics Market Size in USD million (2023-2034)
- Rest of Europe Neuroprosthetics Market Size in USD million (2023-2034)
- Asia-Pacific Neuroprosthetics Market
- China Neuroprosthetics Market Size in USD million (2023-2034)
- Japan Neuroprosthetics Market Size in USD million (2023-2034)
- India Neuroprosthetics Market Size in USD million (2023-2034)
- Australia Neuroprosthetics Market Size in USD million (2023-2034)
- South Korea Neuroprosthetics Market Size in USD million (2023-2034)
- Rest of Asia-Pacific Neuroprosthetics Market Size in USD million (2023-2034)
- Rest of the World (RoW) Neuroprosthetics Market
- Middle East Neuroprosthetics Market Size in USD million (2023-2034)
- Africa Neuroprosthetics Market Size in USD million (2023-2034)
- South America Neuroprosthetics Market Size in USD million (2023-2034)
Neuroprosthetics Market Recent Industry Trends and Milestones (2023-2026)
|
Category |
Key Developments |
|
Neuroprosthetics Market Product Approval |
Manufacturers secured FDA clearances and CE markings for neurostimulation and cochlear implant systems; the FDA granted breakthrough device designations to novel neurotechnologies, including brain-computer interfaces; Nevro and others expanded spinal cord stimulation indications; the European Medical Device Regulation continued to shape requirements. |
|
Neuroprosthetics Market Product Expansion |
Medtronic advanced adaptive deep brain stimulation; Boston Scientific and Abbott expanded DBS and SCS; Cochlear, Sonova, MED-EL, and Demant advanced cochlear implants; Synchron and Blackrock Neurotech advanced brain-computer interfaces; NeuroPace advanced responsive neurostimulation. |
|
Neuroprosthetics Market Product Investment |
Substantial venture investment flowed into brain-computer interfaces and neurotechnology; companies invested in closed-loop and adaptive stimulation, next-generation cochlear implants, and neural interfaces; providers invested in neurosurgical and cochlear implant capacity. |
|
Neuroprosthetics Market Company Strategy |
Medtronic plc, Boston Scientific Corporation, and Abbott Laboratories: Deep brain and spinal cord stimulation leadership. Cochlear Limited, Sonova Holding AG, and MED-EL Medical Electronics: Cochlear implants. LivaNova PLC, NEVRO CORP., and NeuroPace, Inc.: VNS, SCS, and responsive neurostimulation. Blackrock Neurotech and emerging developers: Brain-computer interfaces. |
|
Neuroprosthetics Market Emerging Technologies |
Closed-loop and adaptive neurostimulation; next-generation cochlear implants and sound processors; implantable and endovascular brain-computer interfaces; high-density and novel neural electrodes; non-invasive stimulation and interfaces; and neural technologies to restore movement, communication, and sensation. |
Neuroprosthetics Market Startup Funding and Investment Trends
Investment in the neuroprosthetics ecosystem has concentrated on brain-computer interfaces and next-generation neural interface technologies. The following companies illustrate recent activity and technology focus.
|
Company |
Total Funding |
Funding Stage |
Main Product |
Core Technology |
|
Synchron, Inc. |
Venture funding |
Growth-stage venture |
Stentrode endovascular brain-computer interface |
Minimally invasive endovascular neural interface for motor and communication restoration |
|
Precision Neuroscience Corporation |
Venture funding |
Growth-stage venture |
Layer 7 Cortical Interface |
Thin-film high-density cortical brain-computer interface |
|
Request for unlocking the report of the @ Neuroprosthetics Market | ||||
Synchron is developing the Stentrode, a minimally invasive endovascular brain-computer interface implanted without open brain surgery to restore communication and control for patients with paralysis, while Precision Neuroscience develops a thin-film, high-density cortical brain-computer interface. Additional capital continues to flow toward brain-computer interfaces, high-density neural electrodes, and next-generation neural interface technologies, reflecting conviction that neural interfaces capable of restoring movement, communication, and sensation represent a transformative frontier. Collectively, these efforts signal sustained and growing investment in advancing neuroprosthetics, particularly brain-computer interfaces, and in addressing severe neurological disability with high unmet need.
Key Takeaways from the Neuroprosthetics Market Report Study
- Market size analysis for the current neuroprosthetics market size (2025) and market forecast for 9 years (2026 to 2034).
- Top key product/technology developments, mergers, acquisitions, partnerships, and joint ventures that happened over the last 3 years.
- Key companies dominating the global neuroprosthetics market.
- Various opportunities available for competitors in the neuroprosthetics market space.
- What are the top-performing segments in 2025? How will these segments perform in 2034?
- Which are the top-performing regions and countries in the current neuroprosthetics market scenario?
- Which are the regions and countries where companies should concentrate their opportunities for neuroprosthetics market growth in the future?
Target audience who can benefit from this neuroprosthetics market report study
- Neuroprosthetics product providers
- Research organizations and consulting companies
- Neuroprosthetics-related organizations, associations, forums, and other alliances
- Government and corporate offices
- Start-up companies, venture capitalists, and private equity firms
- Distributors and traders dealing in neuroprosthetic devices
- Various end-users who want to know more about the neuroprosthetics market and the latest technological developments in the neuroprosthetics market.