Aesthetic Implants Market Summary
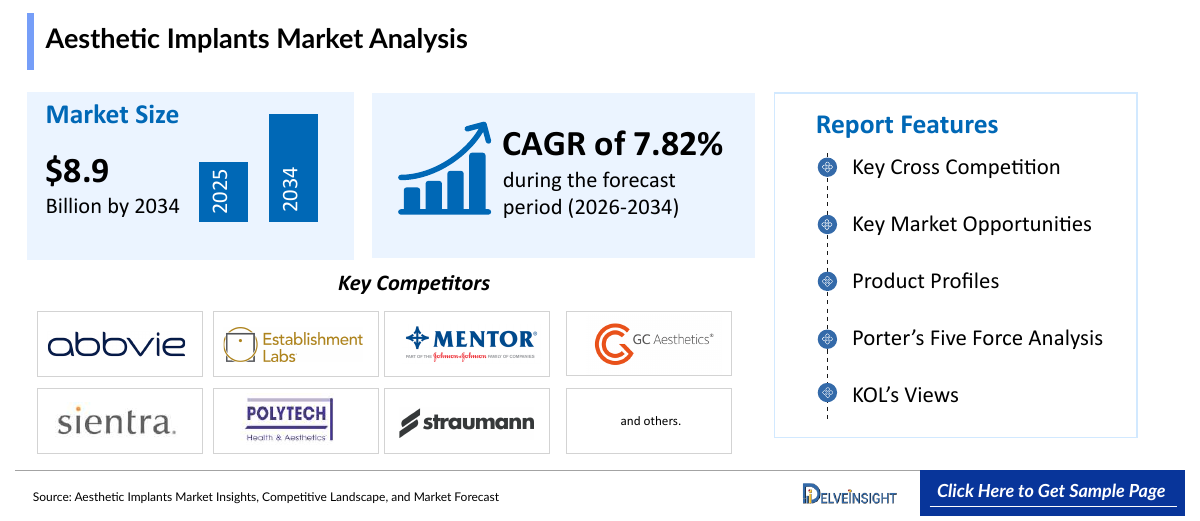
- The Aesthetic Implants market is estimated at USD 4.5 billion in 2025 and is projected to reach USD 8.9 billion by 2034. Growth is anchored in rising demand for cosmetic and reconstructive procedures, an aging global population, expanding medical tourism, and continued innovation in implant materials and designs.
- The global Aesthetic Implants market is growing at a CAGR of 7.82% during the forecast period from 2026 to 2034.
- By product type, the breast implants segment dominated the Aesthetic Implants market with a 45% share in 2025.
- By material, the silicone segment dominated the Aesthetic Implants market with a share of 55% in 2025.
- By gender, the female segment dominated the Aesthetic Implants market with a share of 82% in 2025.
- By end user, the hospitals segment dominated the Aesthetic Implants market with a share of 40% in 2025.
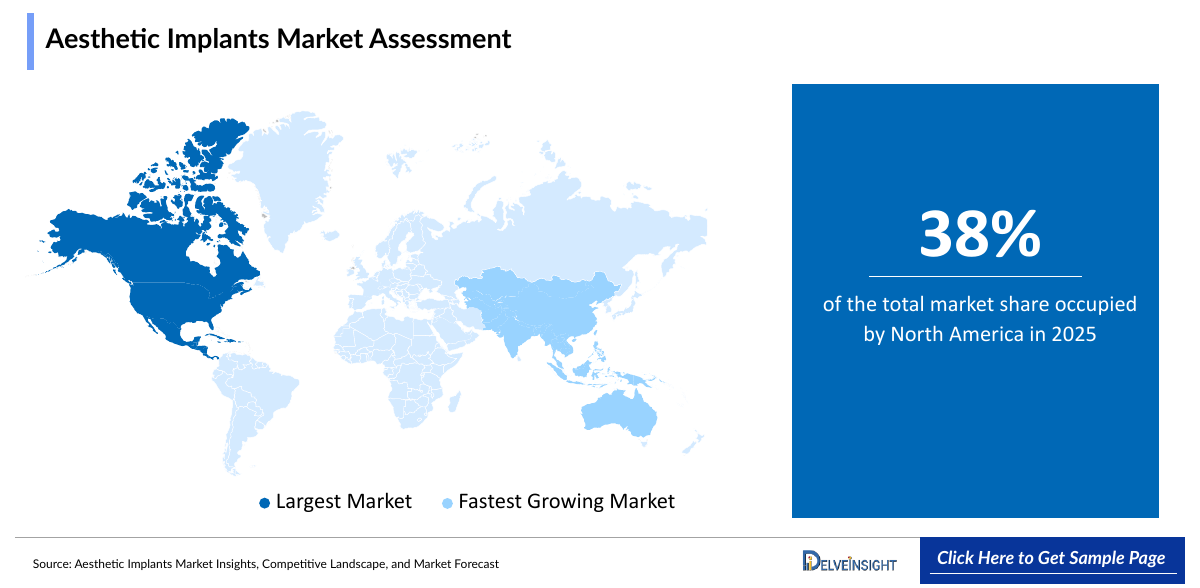
- North America dominated the global Aesthetic Implants market revenue with a share of 38% in 2025, representing the highest regional market share globally.
Aesthetic implants are medical devices surgically placed in the body to enhance, restore, or reconstruct physical appearance for cosmetic and reconstructive purposes. The category spans breast implants used for augmentation and reconstruction, body contouring implants such as gluteal, calf, and pectoral implants, custom-made implants engineered for individual anatomy, nasal implants used in rhinoplasty, dental implants used to restore the dentition and support facial aesthetics, and other facial and chin implants. These devices are manufactured from silicone, saline, polymer, metal, titanium, and composite materials, and are used across hospitals, cosmetology and dermatology clinics, and ambulatory surgical centers. The market is served by established manufacturers including AbbVie through Allergan Aesthetics, Establishment Labs, Mentor Worldwide under Johnson & Johnson, GC Aesthetics, Sientra, and POLYTECH Health and Aesthetics in the breast and body segments, together with Institut Straumann and Dentsply Sirona in dental implants and Integra LifeSciences and Zimmer Biomet in facial and reconstructive implants. Aesthetic implants address cosmetic enhancement, post-mastectomy and trauma reconstruction, congenital correction, and tooth loss, and are distributed through direct manufacturer sales, specialized aesthetic device distributors, and hospital and clinic procurement. Over the past decade, the field has advanced from standard silicone and saline devices toward highly cohesive gel implants, structured and shaped designs, nano-textured and smooth surfaces, and custom patient-specific implants. Driven by rising aesthetic awareness, an aging population, expanding access, and continued innovation, the aesthetic implants market is a large and steadily growing segment of the medical aesthetics industry.
Aesthetic Implants Market Key Growth Drivers
- Rising demand for cosmetic and aesthetic procedures, driven by growing beauty consciousness, social media influence, and greater acceptance of elective aesthetic surgery, is expanding the market.
- The aging global population and increasing demand for reconstructive procedures, including post-mastectomy breast reconstruction and facial reconstruction, are broadening the patient base.
- Continued innovation in implant materials and designs, including highly cohesive silicone gel, structured implants, and nano-textured surfaces, is improving outcomes and safety.
- The expansion of medical tourism and the growing availability of affordable aesthetic procedures in emerging markets are increasing procedure volumes.
- Growth of custom-made and patient-specific implants, enabled by three-dimensional imaging and printing, is expanding the range of aesthetic and reconstructive solutions.
- Rising disposable incomes, expanding aesthetic clinic networks, and increasing awareness of dental and facial aesthetics are broadening demand across regions.
- The convergence of aesthetic demand, reconstructive need, and material innovation is expected to sustain steady growth in the global Aesthetic Implants market through 2034.
Key Companies in Aesthetic Implants Market
The competitive landscape is led by the following active manufacturers and developers of aesthetic implants:
- AbbVie Inc. (Allergan Aesthetics)
- Establishment Labs S.A.
- Mentor Worldwide LLC (Johnson & Johnson)
- GC Aesthetics plc
- Sientra, Inc.
- POLYTECH Health & Aesthetics GmbH
- Institut Straumann AG
- Dentsply Sirona Inc.
- Integra LifeSciences Holdings Corporation
- Zimmer Biomet Holdings, Inc.
For illustrative purposes, only the top 10 companies are listed in the Table of Contents. The report may include analysis and references to additional companies relevant to the market assessment.
Aesthetic Implants Market Size
The following snapshot summarizes the principal report metrics for the Aesthetic Implants market.
|
Report Metrics |
Details |
|
2025 Market Size |
USD 4.5 billion |
|
2034 Projected Market Size |
USD 8.9 billion |
|
Growth Rate (2026-2034) |
7.82% CAGR |
|
Largest Market |
North America |
|
Fastest Growing Market |
Asia-Pacific |
|
Market Structure |
Fragmented |
All market values are expressed in USD and represent DelveInsight estimates synthesized from primary and secondary research.
Factors Contributing to the Growth of the Aesthetic Implants Market
Market Drivers
Rising Demand for Cosmetic and Aesthetic Procedures
The rising demand for cosmetic and aesthetic procedures is the foundational driver of the aesthetic implants market. Growing beauty consciousness, the pervasive influence of social media and visual culture, and the broad social acceptance of elective aesthetic surgery have substantially increased the number of people seeking breast augmentation, body contouring, facial enhancement, and related procedures. Aesthetic procedure volumes have grown steadily across both surgical and non-surgical categories, and implant-based surgical procedures remain central to the field. Greater awareness, destigmatization, and the availability of experienced aesthetic surgeons expand the addressable population. As beauty consciousness and acceptance of aesthetic surgery continue to grow worldwide, demand for aesthetic implants is expected to rise, reinforcing sustained market growth throughout the forecast period.
Aging Population and Reconstructive Demand
The aging global population and the increasing demand for reconstructive procedures are substantial drivers of the market. An aging population seeks facial and body procedures to address the effects of aging, while the rising incidence of breast cancer and the growing adoption of post-mastectomy breast reconstruction expand demand for breast implants in reconstructive settings. Reconstructive needs arising from trauma, congenital conditions, and surgical resection further broaden the patient base across breast, facial, and body implants. Tooth loss, which rises with age, drives demand for dental implants that restore both function and facial aesthetics. As the global population ages and reconstructive procedures become more widely adopted and accessible, demand for aesthetic and reconstructive implants is expected to grow across the forecast period.
Innovation in Implant Materials and Designs
Continued innovation in implant materials and designs is a defining driver of the market. Advances in highly cohesive silicone gel, structured and shaped implants, nano-textured and smooth surface technologies, and improved shell designs have enhanced the safety, durability, natural appearance, and patient satisfaction of breast and body implants. Dental implant innovation in titanium and ceramic materials and surface treatments improves osseointegration and outcomes. Manufacturers such as Establishment Labs with its Motiva implants, AbbVie through Allergan Aesthetics, and others continue to introduce next-generation devices. These innovations address safety concerns, improve results, and expand candidacy. As implant materials and designs continue to advance, technological innovation is expected to be a significant driver of market growth and differentiation across the forecast period.
Expanding Access and Medical Tourism
The expansion of access to aesthetic procedures and the growth of medical tourism are substantial drivers of the market. The proliferation of aesthetic and cosmetology clinics, ambulatory surgical centers, and dental implant centers, together with rising disposable incomes, broadens access to implant-based procedures across regions. Medical tourism, in which patients travel to countries offering high-quality, lower-cost aesthetic and dental procedures, has grown significantly, with destinations across Asia, Latin America, and Europe attracting large procedure volumes. The availability of experienced surgeons and competitive pricing in emerging markets expands the global patient base. As access expands and medical tourism continues to grow, these forces are expected to be an important driver of market growth across the forecast period, particularly in emerging markets.
Growth of Custom-Made and Patient-Specific Implants
The growth of custom-made and patient-specific implants is an increasingly important driver of the market. Advances in three-dimensional imaging, computer-aided design, and three-dimensional printing enable the production of implants engineered to individual patient anatomy, improving fit, aesthetic outcome, and function across facial, cranial, breast, and body applications. Custom implants address complex reconstructive and aesthetic cases that standard devices cannot optimally serve, and growing surgeon and patient interest in personalized solutions expands this segment. Manufacturers and specialized providers increasingly offer patient-specific implant services. As digital design and additive manufacturing technologies mature and personalized aesthetic solutions gain adoption, custom-made implants are expected to be an important driver of market growth and innovation across the forecast period.
Rising Awareness of Dental and Facial Aesthetics
Rising awareness of dental and facial aesthetics is a meaningful driver of the market. Growing emphasis on dental health and smile aesthetics, together with an aging population experiencing tooth loss, has substantially increased demand for dental implants that restore both function and facial appearance, a segment led by manufacturers such as Institut Straumann and Dentsply Sirona. Increasing awareness of facial contouring, chin and cheek enhancement, and rhinoplasty broadens demand for facial and nasal implants. Expanding dental and aesthetic clinic networks, improving affordability, and greater patient awareness drive procedure volumes. As awareness of dental and facial aesthetics continues to grow and access expands, this driver is expected to support market growth across the forecast period, particularly within the dental and facial implant segments.
Market Restraints
Despite strong growth potential, the Aesthetic Implants market faces material constraints. The high cost of implant-based aesthetic and reconstructive procedures, which are largely elective and often not covered by insurance, limits access for many patients and makes demand sensitive to economic conditions. Surgical risks and complications, including capsular contracture, implant rupture, infection, malposition, and the need for revision surgery, together with heightened safety scrutiny, temper adoption. Regulatory and safety concerns, including the association of certain textured breast implants with breast implant-associated anaplastic large cell lymphoma, market withdrawals of specific products, and evolving regulatory requirements from the Food and Drug Administration and under the European Medical Device Regulation, raise compliance burdens and can affect patient confidence. The need for revision and replacement, and the finite lifespan of many implants, add cost and complexity. Competition from non-surgical aesthetic alternatives such as injectables, fillers, fat grafting, and energy-based devices diverts some demand away from implant-based procedures. A shortage of highly trained aesthetic and reconstructive surgeons in some regions constrains capacity, and cultural and social attitudes in certain markets limit demand. Finally, product liability litigation and reputational risk associated with implant safety issues can constrain parts of the market across the forecast period.
Aesthetic Implants Market Segment Analysis
The Aesthetic Implants Market is segmented by Product Type (Breast Implants, Body Contouring Implants, Custom-Made Implants, Nasal Implants, Dental Implants, Others), Material (Silicone, Saline, Polymer, Metal and Titanium, Composite and Others), Gender (Female, Male), End User (Hospitals, Cosmetology Clinics, Ambulatory Surgical Centers), and Geography (North America, Europe, Asia-Pacific, Rest of World).
By Product Type
Dominant Subsegment: Breast Implants.
The breast implants segment accounted for 45% of the Aesthetic Implants market in 2025. Breast implants dominate because they are the most widely used aesthetic implant, employed for both cosmetic breast augmentation, one of the most commonly performed aesthetic surgical procedures worldwide, and post-mastectomy and reconstructive surgery. The large volume of augmentation and reconstruction procedures, the established base of manufacturers including AbbVie through Allergan Aesthetics, Mentor Worldwide under Johnson & Johnson, Establishment Labs, GC Aesthetics, Sientra, and POLYTECH, and continued innovation in silicone gel and structured devices drive the largest share of the market. Dental implants represent a very large and fast-growing segment supporting both function and facial aesthetics, led by Institut Straumann and Dentsply Sirona. Body contouring implants, including gluteal, calf, and pectoral implants, custom-made implants engineered to individual anatomy, and nasal implants used in rhinoplasty each represent important segments, while other facial and chin implants add further categories. Nonetheless, the large procedure volumes, established manufacturer base, and continued innovation in breast implants secure the leadership of this segment across the forecast period, with dental and custom implants growing rapidly.
By Material
Dominant Subsegment: Silicone.
The silicone segment accounted for 55% of the Aesthetic Implants market in 2025. Silicone dominates because it is the predominant material in breast implants, the largest product segment, and is widely used across facial, body, and nasal implants. Modern silicone breast implants use highly cohesive silicone gel that provides a natural look and feel, improved safety, and greater durability, and silicone is the material of choice for most augmentation and reconstruction procedures offered by leading manufacturers such as AbbVie, Mentor, Establishment Labs, GC Aesthetics, Sientra, and POLYTECH. The biocompatibility, versatility, and established clinical use of silicone drive the largest share of the market. Saline remains an established material for breast implants valued for its safety profile and adjustability. Polymer materials are used across various facial and body implants, while metal and titanium dominate dental implants through their osseointegration and strength and are used in certain facial and cranial implants. Composite and other materials, including ceramics and combinations, add further options. Nonetheless, the predominance of silicone in breast and facial implants secures the leadership of this segment across the forecast period, with titanium central to the fast-growing dental segment.
By Gender
Dominant Subsegment: Female.
The female segment accounted for 82% of the Aesthetic Implants market in 2025. The female segment dominates because women account for the large majority of aesthetic implant procedures, driven primarily by breast augmentation and reconstruction, which are performed predominantly in women, as well as high rates of facial, body contouring, and aesthetic procedures. Women represent the overwhelming majority of breast implant recipients in both cosmetic and reconstructive settings, and also account for a large share of facial, nasal, and body aesthetic procedures, driving the dominant share of the market. The male segment represents a smaller but steadily growing portion of the market, driven by rising demand among men for pectoral and calf implants, facial and chin augmentation, dental implants, and other aesthetic procedures, supported by growing acceptance of male aesthetic surgery. Nonetheless, the predominance of breast and aesthetic procedures performed in women secures the leadership of the female segment across the forecast period, with the male segment growing as male aesthetic demand expands.
By End User
Dominant Subsegment: Hospitals.
The hospitals segment accounted for 40% of the Aesthetic Implants market in 2025. Hospitals dominate because many implant-based aesthetic and reconstructive procedures, particularly breast reconstruction, complex and custom reconstructive implants, and procedures requiring general anesthesia and comprehensive surgical and post-operative care, are performed in hospital settings with full surgical infrastructure and multidisciplinary support. The volume of reconstructive and complex aesthetic surgery performed in hospitals, together with their established surgical capabilities, drives the largest share of the market. Cosmetology and dermatology clinics represent a large and growing segment that performs high volumes of elective cosmetic implant procedures, including breast augmentation and facial and body aesthetics, in specialized outpatient settings, and are central to the aesthetic market. Ambulatory surgical centers represent a fast-growing segment offering cost-effective, convenient outpatient surgery for many implant procedures. Nonetheless, the concentration of reconstructive and complex procedures and comprehensive surgical infrastructure in hospitals secures the leadership of this segment across the forecast period, with clinics and ambulatory surgical centers growing as outpatient aesthetic procedures expand.
Aesthetic Implants Market Region Analysis
North America accounted for 38% of the global Aesthetic Implants market revenue in 2025, representing the highest regional market share globally. The region's dominance reflects high aesthetic procedure volumes, strong consumer spending on cosmetic and reconstructive surgery, advanced healthcare infrastructure, early adoption of innovative implants, and the presence of major manufacturers. The United States leads on the strength of one of the world's largest aesthetic surgery markets, high rates of breast augmentation and reconstruction, dental implant adoption, high disposable incomes, and the presence of companies such as AbbVie through Allergan Aesthetics, Mentor under Johnson & Johnson, Sientra, and Establishment Labs' commercial operations. The regulatory environment is well established, with the Food and Drug Administration providing oversight of breast and other implants, including safety requirements and post-market surveillance. Strong consumer demand, established aesthetic surgery practices, and early adoption of new devices reinforce the market. This combination of high procedure volumes, consumer spending, and innovation reinforces North America's leadership in the global market.
Fastest Growing Region: Asia-Pacific
Asia-Pacific is the fastest-growing region in the Aesthetic Implants market. The region's elevated CAGR is driven by rapidly rising aesthetic awareness, growing disposable incomes, large and expanding populations, the booming medical tourism industry, and the strong cultural emphasis on aesthetics in several markets. Countries such as South Korea, widely regarded as a global center for aesthetic surgery, together with China, Japan, India, Thailand, and others, generate large and growing procedure volumes across breast, facial, dental, and body implants. Expanding aesthetic and dental clinic networks, rising middle-class spending, growing acceptance of aesthetic surgery, and significant inbound medical tourism broaden access and demand. Both regional and multinational manufacturers are expanding their presence. The combination of rising aesthetic demand, growing affluence, large populations, and thriving medical tourism positions Asia-Pacific as the highest-growth region over the forecast period.
Regional Commentary
North America
North America accounted for 38% of the global Aesthetic Implants market revenue in 2025. The United States dominates the region on the strength of one of the world's largest aesthetic surgery markets, high breast augmentation and reconstruction volumes, strong dental implant adoption, and the presence of major manufacturers, while Canada contributes through its aesthetic and healthcare sector and Mexico combines domestic demand with a large medical tourism industry.
Europe
Europe represents a major regional market, led by Germany, France, Italy, and the United Kingdom, and home to manufacturers such as POLYTECH Health and Aesthetics, GC Aesthetics, Institut Straumann, and Dentsply Sirona's European operations. Growth is supported by established aesthetic and dental surgery, while the European Medical Device Regulation shapes product requirements and safety standards across the region.
Asia-Pacific
Asia-Pacific is the fastest-growing region, propelled by rapidly rising aesthetic awareness, growing disposable incomes, large populations, and a booming medical tourism industry across South Korea, China, Japan, India, and Thailand. Expanding clinic networks and strong cultural emphasis on aesthetics are broadening demand across breast, facial, dental, and body implants.
Rest of World
The Rest of World region, spanning Latin America, the Middle East, and Africa, is an important and growing market. Brazil in particular is one of the world's largest aesthetic surgery markets, and the Middle East shows strong demand, while expanding access, rising incomes, and growing medical tourism broaden adoption across the region.
Aesthetic Implants Market Competitive Landscape
The Aesthetic Implants market is classified as Fragmented. The market comprises several established manufacturers across distinct implant categories, including AbbVie through Allergan Aesthetics, Establishment Labs, Mentor Worldwide under Johnson & Johnson, GC Aesthetics, Sientra, and POLYTECH in breast and body implants, Institut Straumann and Dentsply Sirona in dental implants, and Integra LifeSciences and Zimmer Biomet in facial and reconstructive implants, with leadership varying by segment and region and no single company dominating the entire market.
The competitive landscape can be evaluated across the following dimensions:
- Market concentration: Fragmented across implant categories, with distinct leaders in breast, dental, and facial segments and no single company dominating the entire market.
- Leading players: AbbVie (Allergan Aesthetics), Establishment Labs, Mentor (Johnson & Johnson), GC Aesthetics, Sientra, and POLYTECH lead in breast and body implants, while Institut Straumann and Dentsply Sirona lead in dental implants.
- Geographic reach: Companies range from global leaders with worldwide operations to strong regional specialists across North America, Europe, and Asia-Pacific.
- Product portfolio strength: Players hold broad portfolios of silicone and saline breast implants, body contouring implants, dental implants, facial implants, and custom solutions.
- Pipeline strength: Active development in next-generation silicone gel implants, structured and nano-textured devices, dental implant systems, and custom patient-specific implants.
- Strategic partnerships: Collaborations with aesthetic surgeons, dental practices, clinics, and distributors shape market reach and adoption.
- M&A and investment activity: The field has seen notable acquisitions, including AbbVie's acquisition of Allergan and Johnson & Johnson's ownership of Mentor, alongside ongoing investment.
- Manufacturing and technology capabilities: Material science, implant surface technology, and custom manufacturing are key competitive differentiators.
- Innovation focus: Highly cohesive silicone gel, structured implants, nano-textured surfaces, improved safety, dental implant systems, and custom patient-specific implants.
Aesthetic Implants Market Recent Developmental Activities
In 2023 and 2024, Establishment Labs continued to expand the commercialization of its Motiva breast implants, including progress in the United States market following regulatory engagement. Strategic significance: Advances a next-generation breast implant platform and expands presence in the largest market.
In 2023 and 2024, AbbVie, through Allergan Aesthetics, continued to market and develop its breast implant and aesthetic portfolio following its acquisition of Allergan. Strategic significance: Sustains the leadership of a major aesthetic implant and medical aesthetics franchise.
In 2023 and 2024, Institut Straumann advanced its dental implant systems and digital dentistry offerings. Strategic significance: Reinforces leadership in the large and fast-growing dental implant segment.
In 2023 and 2024, Dentsply Sirona advanced its dental implant and digital workflow portfolio. Strategic significance: Strengthens its position in dental implants and aesthetic dentistry.
In 2023 and 2024, GC Aesthetics and Sientra continued to develop and market their breast implant portfolios. Strategic significance: Sustains competition and choice in the breast implant segment.
In 2023 and 2024, POLYTECH Health and Aesthetics advanced its breast and body implant offerings in Europe and internationally. Strategic significance: Reinforces the European breast and body implant segment.
In 2023 and 2024, regulatory agencies, including the Food and Drug Administration, continued post-market surveillance and safety requirements for breast implants, including labeling and screening guidance. Strategic significance: Shapes safety standards and manufacturer requirements across the market.
In 2023 and 2024, the European Medical Device Regulation continued to shape requirements for aesthetic and reconstructive implants in Europe. Strategic significance: Raises compliance requirements and influences product and market-entry strategies.
In 2023 and 2024, manufacturers advanced custom and patient-specific implant solutions enabled by three-dimensional imaging and printing. Strategic significance: Expands personalized aesthetic and reconstructive implant options.
In 2023 and 2024, continued growth in aesthetic procedure volumes and medical tourism, particularly in Asia-Pacific and Latin America, expanded demand. Strategic significance: Underscores the global demand base driving the market.
In 2023 and 2024, Integra LifeSciences and Zimmer Biomet continued to offer facial, cranial, and reconstructive implant solutions. Strategic significance: Reinforces the facial and reconstructive implant segment.
In 2023 and 2024, innovation in highly cohesive silicone gel, structured implants, and surface technologies advanced across manufacturers. Strategic significance: Improves implant safety, outcomes, and differentiation.
Aesthetic Implants Market Segmentation
Aesthetic Implants Market by Product Type
- Breast Implants
- Body Contouring Implants
- Custom-Made Implants
- Nasal Implants
- Dental Implants
- Others
Aesthetic Implants Market by Material
- Silicone
- Saline
- Polymer
- Metal and Titanium
- Composite and Others
Aesthetic Implants Market by Gender
- Female
- Male
Aesthetic Implants Market by End User
- Hospitals
- Cosmetology Clinics
- Ambulatory Surgical Centers
Aesthetic Implants Market by Geography
- North America Aesthetic Implants Market
- United States Aesthetic Implants Market Size in USD million (2023-2034)
- Canada Aesthetic Implants Market Size in USD million (2023-2034)
- Mexico Aesthetic Implants Market Size in USD million (2023-2034)
- Europe Aesthetic Implants Market
- Germany Aesthetic Implants Market Size in USD million (2023-2034)
- United Kingdom Aesthetic Implants Market Size in USD million (2023-2034)
- France Aesthetic Implants Market Size in USD million (2023-2034)
- Italy Aesthetic Implants Market Size in USD million (2023-2034)
- Spain Aesthetic Implants Market Size in USD million (2023-2034)
- Rest of Europe Aesthetic Implants Market Size in USD million (2023-2034)
- Asia-Pacific Aesthetic Implants Market
- China Aesthetic Implants Market Size in USD million (2023-2034)
- Japan Aesthetic Implants Market Size in USD million (2023-2034)
- India Aesthetic Implants Market Size in USD million (2023-2034)
- Australia Aesthetic Implants Market Size in USD million (2023-2034)
- South Korea Aesthetic Implants Market Size in USD million (2023-2034)
- Rest of Asia-Pacific Aesthetic Implants Market Size in USD million (2023-2034)
- Rest of the World (RoW) Aesthetic Implants Market
- Middle East Aesthetic Implants Market Size in USD million (2023-2034)
- Africa Aesthetic Implants Market Size in USD million (2023-2034)
- South America Aesthetic Implants Market Size in USD million (2023-2034)
Aesthetic Implants Market Recent Industry Trends and Milestones (2023-2026)
|
Category |
Key Developments |
|
Aesthetic Implants Market Product Approval |
Regulatory agencies, including the FDA, continued post-market surveillance, labeling, and screening requirements for breast implants; Establishment Labs advanced U.S. market access for its Motiva implants; the European Medical Device Regulation continued to shape requirements for aesthetic and reconstructive implants. |
|
Aesthetic Implants Market Product Expansion |
Establishment Labs expanded Motiva commercialization; AbbVie advanced its Allergan Aesthetics portfolio; Institut Straumann and Dentsply Sirona advanced dental implant systems; GC Aesthetics, Sientra, and POLYTECH advanced breast implant portfolios; Integra and Zimmer Biomet advanced facial and reconstructive implants. |
|
Aesthetic Implants Market Product Investment |
The field saw investment in next-generation silicone gel and structured implants, dental implant systems, and custom patient-specific implants, alongside major transactions such as AbbVie's acquisition of Allergan. |
|
Aesthetic Implants Market Company Strategy |
AbbVie (Allergan Aesthetics), Establishment Labs, Mentor (Johnson & Johnson), GC Aesthetics, Sientra, and POLYTECH: Breast and body implants. Institut Straumann and Dentsply Sirona: Dental implants. Integra LifeSciences and Zimmer Biomet: Facial and reconstructive implants. |
|
Aesthetic Implants Market Emerging Technologies |
Highly cohesive silicone gel implants; structured and nano-textured surface devices; advanced dental implant and digital dentistry systems; three-dimensional imaging and printing for custom patient-specific implants; and improved safety and surveillance technologies. |
Aesthetic Implants Market Startup Funding and Investment Trends
Investment in the aesthetic implant ecosystem has concentrated on next-generation breast implants, advanced dental implant systems, and custom patient-specific solutions. The following companies illustrate recent activity and technology focus.
|
Company |
Total Funding |
Funding Stage |
Main Product |
Core Technology |
|
Establishment Labs S.A. |
Public and venture-backed |
Public (growth-stage) |
Motiva breast implants |
Next-generation silicone gel breast implants with advanced surface and shell technology designed for safety and natural results |
|
Sientra, Inc. |
Public and restructured |
Public / restructuring |
Breast implants and aesthetic portfolio |
Silicone gel breast implants and aesthetic devices for augmentation and reconstruction |
|
Request for unlocking the report of the @ Aesthetic Implants Market | ||||
Establishment Labs develops the Motiva platform, a next-generation breast implant designed for improved safety, natural appearance, and patient satisfaction, while Sientra offers silicone gel breast implants and aesthetic products for augmentation and reconstruction. Additional capital continues to flow toward advanced breast implants, dental implant systems, and custom patient-specific implant technologies, reflecting conviction that innovation in implant materials, surfaces, and personalization addresses great and growing aesthetic and reconstructive demand. Collectively, these efforts signal sustained investment in advancing implant safety, improving outcomes, and expanding the range of aesthetic and reconstructive solutions.
Key Takeaways from the Aesthetic Implants Market Report Study
- Market size analysis for the current aesthetic implants market size (2025), and market forecast for 9 years (2026 to 2034).
- Top key product/technology developments, mergers, acquisitions, partnerships, and joint ventures that happened over the last 3 years.
- Key companies dominating the global aesthetic implants market.
- Various opportunities available for competitors in the aesthetic implants market space.
- What are the top-performing segments in 2025? How will these segments perform in 2034?
- Which are the top-performing regions and countries in the current aesthetic implants market scenario?
- Which are the regions and countries where companies should concentrate their opportunities for aesthetic implants market growth in the future?
Target audience that can benefit from this aesthetic implants market report study
- Aesthetic Implants manufacturers and product providers
- Research organizations and consulting companies
- Aesthetic Implants-related organizations, associations, forums, and other alliances
- Government and corporate offices
- Start-up companies, venture capitalists, and private equity firms
- Distributors and traders dealing in aesthetic implants
- Various end-users who want to know more about the aesthetic implants market and the latest technological developments in the aesthetic implants market.